
Blogs
PW Consulting: Used Cooking Oil for SAF Market Hits $2.87B in 2025, Projected 20.31% CAGR to $10.45B by 2032
By pmarketresearch, 2026-09-16
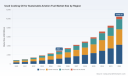
The UCO-to-SAF Imperative: Navigating a $10 Billion Transition by 2032
The aviation industry stands at a critical decarbonization inflection point, and used cooking oil has emerged as one of the most strategically vital feedstock vectors in the sustainable aviation fuel value chain. Our latest market research on the Used Cooking Oil for Sustainable Aviation Fuel market translates a rapidly compounding revenue trajectory into an actionable decision framework for executives, procurement leaders, and energy investors. Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, the analysis captures how feedstock logistics, regulatory mandates, and refining pathway economics are converging to reshape competitive positioning across the global SAF ecosystem.
The headline trajectory is unmistakable. Revenue associated with UCO directed toward sustainable aviation fuel applications expanded from roughly $840 million in 2020 to approximately $2.87 billion in 2025, and the forecast arc accelerates sharply thereafter, reaching an estimated $3.49 billion in 2026 and climbing toward $10.45 billion by 2032. This expansion is anchored by a projected compound annual growth rate of 20.31 percent across the 2026–2032 forecast period. For strategy teams, the implication is straightforward: UCO is no longer a peripheral waste-stream story. It is becoming a structurally constrained, policy-driven commodity whose availability, pricing power, and geographic routing will determine which refiners, aggregators, and airline-affiliated fuel buyers can reliably meet blending obligations without incurring margin erosion.
Executing in this environment requires more than top-line forecasting. It demands a clear line of sight into collection-channel economics, conversion-pathway competitiveness, regional supply-chain resilience, and the contractual architectures that major processors are already locking in. The research is designed to deliver that precision without overwhelming decision-makers with undifferentiated data density. Instead, it surfaces the operational and strategic variables that actually move the needle when boards are allocating capital, negotiating offtake terms, or evaluating entry into the HEFA and co-processing value chains.
Why This Research Matters for 2026 Decision-Making
2026 is a pivot year for sustainable aviation fuel procurement and feedstock strategy. Regulatory clocks have already started ticking in key markets, and the earliest compliance cycles are exposing the operational realities of scaling UCO-dependent production. The European Union’s ReFuelEU Aviation mandate requires a 2 percent SAF blending baseline from January 2025, climbing toward 6 percent by 2030, with UCO-based HEFA positioned as the dominant compliant pathway in the near term. In the United Kingdom, the SAF mandate took effect in January 2025 with a 2 percent target, and provisional data from the first ten months of 2025 indicated that 1.63 percent was achieved, entirely from UCO feedstock. These early compliance readings matter because they reveal both the speed at which demand can materialize and the dependency that emerges when a single feedstock category carries the bulk of early blending requirements.
On the incentive side, the United States Section 45Z clean fuel production credit provides up to $1 per gallon for SAF through 2029 under updated legislation, with eligibility restricted to North American feedstocks. That restriction changes the strategic calculus for anyone modelling U.S. production economics or planning feedstock sourcing across borders. Meanwhile, trade dynamics are reshaping physical supply routes: U.S. imports of UCO from China declined significantly in 2025 due to tariff pressure, pushing sourcing activity toward Australia, South Korea, and Malaysia even as total import volumes remained robust at approximately 2 million metric tons through November 2025. These are exactly the kinds of structural shifts that can undermine a supply plan if they are treated as background noise rather than core inputs to scenario design.
Used Cooking Oil for Sustainable Aviation Fuel Market
The research therefore treats feedstock availability as a strategic risk variable, not a static assumption. It maps how collection infrastructure, pre-processing capacity, and long-term supply commitments interact with policy timelines, so that executives can stress-test their SAF sourcing strategies against realistic constraints instead of optimistic averages.
What the Report Covers: An Operational Roadmap, Not Just a Forecast
The study is built around practical decision support. Beyond the macro revenue trajectory and multi-year forecast, the report examines the structural segmentation that determines where value accrues and where bottlenecks form. It analyzes collection and supply channels including food service collection, industrial food processing, and household collection, with attention to how each channel’s logistics profile affects scalability, contamination risk, and feedstock consistency. It also evaluates application pathways, particularly the HEFA production pathway and refinery co-processing, explaining how capital intensity, conversion yields, and integration with existing refining assets shape competitiveness across different operator profiles.
Worldwide Kenaf Seed Oil Market
Regional analysis is presented to help teams understand where supply depth, processing infrastructure, and policy momentum are most aligned. Rather than forcing a single narrative, the research disaggregates market behavior so that strategy leaders can identify which geographies offer the most reliable feedstock aggregation, where co-processing assets are best positioned to absorb waste oils, and where import dependency may create vulnerability under shifting trade or tariff regimes.
Equally important, the report connects quantitative structure to real-world industry movement. It incorporates recent developments that illustrate how the market is actually behaving as procurement contracts, production ramp-ups, and partnership agreements begin to lock in supply for the 2026–2030 window. These activity signals are essential for interpreting whether observed price behavior reflects temporary tightness or a more durable re-rating of UCO as a premium SAF feedstock.
Competitive Positioning in a Concentrated but Fragmented Value Chain
The competitive landscape reveals a market that is consolidated at the top yet highly dependent on a broad network of collectors, processors, and integrators. Market concentration data indicates a CR3 of approximately 38.4 percent and a CR5 of about 52.15 percent, suggesting that while leading players hold meaningful share, a substantial portion of supply and conversion capacity remains distributed across specialized operators. For entrants and incumbents alike, the strategic question is less about aggregate share than about securing dependable feedstock flow, differentiating by conversion route, and building long-term contractual insulation against price volatility.
Among the most prominent players, Neste stands out as a global leader in renewable fuels with extensive UCO collection and processing networks, including assets acquired in the United States, feeding HEFA-based SAF production across multiple refineries through dedicated UCO-to-SAF pathways. Darling Ingredients operates through its Diamond Green Diesel joint venture, supplying UCO and other waste feedstocks and delivering neat SAF produced from UCO, animal fats, and other renewables. Greenergy International functions as a major collector and supplier of UCO for biofuel and SAF production, supported by established European and international aggregation networks that reinforce HEFA pathway supply. In the UK, Olleco specializes in UCO collection and pre-processing for conversion into biodiesel and SAF feedstocks, while Brocklesby Ltd collects and processes UCO into refined feedstock specifically for sustainable aviation fuel production. Argent Energy focuses on waste-based feedstocks including UCO for advanced biofuels and SAF.
Across the Atlantic, Baker Commodities Inc. provides UCO collection and recycling services that supply feedstock for renewable diesel and SAF facilities, and Mahoney Environmental Inc. operates as a UCO collection specialist delivering feedstock directly into Neste’s SAF production. Quatra supplies large volumes of European UCO under long-term agreements for processing into SAF at biorefineries. Sanimax collects and processes animal fats and UCO for renewable fuel and SAF applications across Canada and the United States. Münzer Bioindustrie GmbH processes UCO and waste oils into biofuels with SAF feedstock capabilities. World Energy operates biorefineries converting UCO into high volumes of SAF. EcoCeres converts UCO and agricultural waste into SAF and other fuels using proprietary technology. In Asia, PT Pertamina has completed its first SAF shipment from UCO and is developing co-processing capabilities for UCO-based SAF, while Sinopec operates UCO-based bio-aviation fuel plants using proprietary SRJET technology. TotalEnergies receives UCO supplies for biorefineries producing SAF and operates co-processing units using waste oils. XCF Global Inc., through its New Rise Renewables operations, runs HEFA SAF facilities using waste- and residue-based feedstocks including UCO.
What makes this competitive set strategically interesting is not simply the roster of names, but the pattern of recent commitments and operational milestones. In August 2025, PT Pertamina completed its first shipment of aviation fuel produced from used cooking oil, signaling state-backed momentum in UCO-based SAF adoption. In July 2025, Quatra signed a 15-year agreement to supply TotalEnergies with 60,000 tons of European used cooking oil annually starting in 2026 for biodiesel and SAF processing, illustrating how long-duration contracts are being used to stabilize feedstock access. In December 2024, Darling Ingredients delivered its first batch of neat SAF produced using UCO and other renewable feedstocks via Diamond Green Diesel to Avfuel Corporation, marking a concrete step in distributed neat-SAF supply. In February 2025, XCF Global’s New Rise Reno facility began ramp-up with HEFA technology using waste feedstocks, with SAF production expected to resume in early 2026. In March 2025, Cosmo Oil partnered with SAFFAIRE SKY ENERGY, Suita City, JGC Holdings, and REVO International to promote domestic UCO collection for Japan’s first large-scale locally-made SAF production targeting 30,000 kiloliters per year.
These moves matter because they show the market hardening around long-term supply architecture. A collector secures a 15-year off-take commitment; a refiner brings a HEFA line back into ramp-up; a state-owned energy company executes its first UCO-based SAF shipment; a domestic consortium organizes around localized collection to reduce import dependency. Each event is a data point in a broader pattern: the companies that can combine reliable collection, credible processing credentials, and policy-aligned conversion pathways are positioning themselves to capture the most durable margins as mandates intensify.
Feedstock Economics, Regulatory Tailwinds, and the 2026–2032 Window
Pricing behavior in the UCO market has become an integral part of SAF project economics. Indicative bulk UCO prices in 2025–2026 reached the $750–$1,250 per ton range in Europe and North America, with spikes above $1,400 per ton in tight markets, driven by rising SAF and biodiesel demand. For procurement and finance teams, this range is not just a commodity note; it is a margin sensitivity variable that interacts directly with blending mandates, incentive eligibility, and the competitiveness of alternative feedstocks. When UCO prices spike, the economic advantage of co-processing configurations, regional sourcing diversification, and long-term fixed-price or indexed contracts becomes more pronounced.
Regulatory alignment is amplifying that sensitivity. The EU ReFuelEU Aviation mandate’s progressive ramp from 2 percent to 6 percent by 2030 establishes a multi-year demand floor that favors feedstocks capable of meeting compliance requirements at scale. UCO-based HEFA has emerged as the dominant compliant pathway in the early years, which means that near-term policy implementation is disproportionately channeling demand toward the very feedstock category this research analyzes. In parallel, the UK mandate’s early attainment figures, entirely from UCO feedstock, underscore how quickly a market can become concentrated around a single supply base when compliance timelines are immediate and alternatives are limited.
In the United States, the Section 45Z credit creates a different kind of strategic filter. Because eligibility is restricted to North American feedstocks, the incentive architecture favors domestic and regionally sourced supply chains over imported alternatives, reinforcing the importance of collection networks, preprocessing capacity, and feedstock traceability within the eligible geography. This is one of the reasons the report pays close attention to how trade flow changes, such as the 2025 decline in U.S. UCO imports from China and the corresponding pivot toward Australia, South Korea, and Malaysia, can alter both cost structures and compliance positioning.
From Intelligence to Action
The broader takeaway for 2026 planning is that UCO for sustainable aviation fuel is evolving from an opportunistic sustainability narrative into a tightly contested supply-chain business. The revenue outlook suggests a market moving toward the $10.45 billion range by 2032, but the strategic prize will not go to organizations that simply recognize the growth trend. It will go to those who can map their feedstock access, conversion strategy, and regulatory exposure onto a coherent plan before mandates, incentives, and competitor contracts reshape the landscape.
This research is designed to support that planning with granular segmentation, competitive profiling, and market-dynamic analysis that can be translated directly into sourcing strategy, capacity evaluation, and risk management. The full study provides the detailed regional and segment breakouts, company-level analysis, and scenario-ready context that executives need to move from awareness to execution. For teams responsible for SAF procurement, renewable fuel investment, or feedstock portfolio strategy, the complete report offers the depth required to make 2026 decisions with confidence rather than conjecture.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive ISOFIX Mounts Reach $1.05B in 2025, Expanding to $1.6B by 2032 at 6.25% CAGR
By pmarketresearch, 2026-09-16
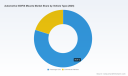
Strategic Imperatives in the Global Automotive ISOFIX Mounts Market: Navigating Growth and Compliance Through 2032
The automotive safety ecosystem is undergoing a fundamental transformation, driven by rigorous regulatory frameworks and an increasing consumer demand for child passenger safety. At the heart of this evolution lies the ISOFIX mounting system, a standardized attachment mechanism that has become critical for securing child restraint systems within vehicles. For industry stakeholders, understanding the trajectory of the Automotive ISOFIX Mounts Market is not merely an exercise in data analysis; it is a strategic necessity for capital allocation, product development, and supply chain resilience.
Our latest comprehensive study, the Worldwide Automotive ISOFIX Mounts Market research, offers a granular view of this sector. This article serves as a strategic briefing, highlighting the macro-economic drivers and regulatory currents shaping the landscape from 2026 through 2032. While we outline the broad contours of opportunity here, the full depth of segmentation, competitive intelligence, and quantitative forecasts is reserved for our detailed report, designed to equip decision-makers with actionable intelligence.
Market Trajectory and Financial Outlook
The financial narrative of the ISOFIX mounts market reflects a steady upward trend, underpinned by vehicle production growth and mandatory safety installations. Analyzing historical data from 2020 to 2025 provides a baseline for understanding market maturity. In 2020, the global market revenue stood at approximately 785.4 million USD. Over the subsequent five years, the market experienced consistent expansion, reaching 1050.0 million USD by the base year of 2025.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with varying rates of acceleration across different phases. The market is projected to surpass the 1.6 billion USD mark by 2032. This growth trajectory is supported by a Compound Annual Growth Rate (CAGR) of 6.25 percent during the forecast period. Such figures indicate a mature yet expanding market where volume growth is often tied to regulatory mandates in emerging automotive hubs and the replacement cycle in established markets.
It is crucial for strategic planners to note that while the aggregate numbers paint a picture of health, the distribution of this value is heavily influenced by regional manufacturing capabilities and vehicle type segmentation. The shift from historical stability to future expansion requires companies to align their capacity planning with these projected revenue milestones, ensuring that infrastructure investments match the anticipated demand surge in the latter half of the decade.
Regulatory Landscape as a Growth Catalyst
Regulations are the primary engine driving standardization and, consequently, market demand for ISOFIX components. The industry is currently navigating a complex web of international safety standards that dictate design specifications and installation protocols.
UNECE Standards and i-Size Mandates
In Europe and many other jurisdictions, the United Nations Economic Commission for Europe (UNECE) regulations hold significant sway. Within UNECE R129, commonly known as i-Size, ISOFIX is mandatory for the i-Size category. This regulation aims to ensure universal vehicle compatibility and significantly reduce incorrect installations, which have historically been a major safety risk. The mandate creates a compliance-driven demand where vehicle manufacturers must equip cars with standardized anchor points, and child seat producers must design around these fixed points.
Furthermore, the evolution of these standards is ongoing. During the GRSP-77 session in May 2025, there was discussion on the potential evolution of ISOFIX 3.0. Building on 30 years of the standardized attachment system, these discussions signal that the technology is not static. Companies must remain agile to adapt to potential iteration in mounting mechanisms or strength requirements that could arise from these standardization bodies.
NHTSA and Side-Impact Protection
In the United States, the National Highway Traffic Safety Administration (NHTSA) continues to tighten safety requirements. Ongoing implementation preparations for FMVSS 213a, focusing on side-impact protection standards, are affecting child restraint systems that utilize ISOFIX mounts. This standard requires enhanced side-impact testing for child car seats under 40 pounds. The compliance date has been extended to December 5, 2026, which impacts the design and validation of ISOFIX-compatible restraints.
This regulatory update creates a specific pressure point for manufacturers. It is not enough to simply meet anchorage strength requirements; the interaction between the mount and the restraint system must withstand higher lateral forces. Anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements to prevent anchorage failure or seat damage during use. For component suppliers, this means material science and structural integrity testing are becoming more critical than ever before.
Competitive Landscape and Key Players
The market structure is characterized by a moderate level of concentration, with key players holding significant sway over supply chains and technological standards. Our analysis indicates a CR3 of 42.5 percent and a CR5 of 58.8 percent, suggesting that while there are dominant entities, there is still room for specialized manufacturers and regional players to capture value.
The competitive environment is defined by companies that specialize in the precision engineering of safety components. Leading entities include:
- Holmbergs (Sweden): This company specializes in ISOFIX/LATCH connectors, arms, straps, tethers, and adjusters. They supply global child car seat manufacturers, focusing on the secure vehicle anchoring ecosystem. Their strategic position lies in their integration with child seat producers who require high-reliability connectors.
- Ningbo Welldon Infant and Child Safety Technology Co., Ltd. (China): As a manufacturer of ISOFIX mounting points, anchors, and related child safety seat components, Welldon represents the significant manufacturing capacity located in Asia. Their focus on automotive applications makes them a key supplier for vehicle OEMs and tier-one safety component integrators.
- IMMI (United States): IMMI produces ISOFIX anchorages, LATCH attachments, snap hooks, and child seating components. They are notable for their compliance with global safety standards including FMVSS and ECE. Their location in the US positions them strategically to navigate North American regulatory changes such as FMVSS 213a.
- Quanzhou Kwok Shing Automotive Subassembly Co., Ltd. (China): This firm supplies ISOFIX systems and rigid baby car seat components as automotive subassemblies. Their role highlights the trend towards modular subassemblies that can be integrated directly into vehicle production lines or child seat manufacturing processes.
These companies are not merely competing on price; they are competing on certification, reliability, and the ability to adapt to evolving regulatory standards. The interplay between Swedish design specialization, American regulatory compliance expertise, and Chinese manufacturing scale defines the current competitive dynamics. Strategic partnerships between vehicle manufacturers and these component suppliers are essential to ensure that the final assembly meets the rigorous crash load requirements.
Technical Dynamics and Material Considerations
The engineering behind ISOFIX mounts is driven by the need for structural integrity under crash loads. ISOFIX mounts and anchors are primarily constructed from high-strength steel or alloy steel. This material choice is non-negotiable, as the components must withstand significant force without deformation or failure during an accident.
The technical specifications are tightly linked to the regulatory environment. ISOFIX anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements. Any deviation can lead to anchorage failure or seat damage during use, posing severe liability risks for automakers and component suppliers. As vehicle designs evolve towards lighter materials and different chassis structures, the integration of these steel mounts becomes a challenge in itself. Engineers must ensure that the mounting points do not compromise the structural integrity of the vehicle floor or seat rails while still providing the rigid connection required for child safety.
Moreover, the supply chain for these high-strength materials is subject to global commodity fluctuations. Strategic procurement strategies are required to mitigate cost volatility without compromising the quality standards mandated by safety regulations.
Strategic Focus for OEMs and Aftermarket
The market is broadly divided by sales channel, with distinct implications for different business models. The Original Equipment Manufacturer (OEM) channel represents the larger portion of the market revenue. This segment is driven by vehicle production volumes and the mandatory inclusion of ISOFIX points in new car models. For suppliers targeting this segment, long-term contracts and qualification processes with automotive OEMs are critical. The revenue flow here is stable but subject to the cycles of the automotive industry.
Conversely, the Aftermarket segment serves a different need. While smaller in total revenue compared to OEM, it represents a vital channel for retrofitting older vehicles or replacing damaged components. As the fleet of vehicles equipped with ISOFIX grows, the aftermarket demand evolves from installation assistance to replacement parts for wear and tear or post-accident repair. Companies operating in this space must maintain broad compatibility across various vehicle models and generations.
Understanding the split between these channels is vital for revenue forecasting. While the OEM channel drives volume through new car sales, the aftermarket offers recurrent revenue opportunities and niche customization possibilities. A balanced portfolio strategy often involves servicing both streams to mitigate the risk of production slowdowns in the automotive sector.
Regional Growth Vectors
Geographically, the market exhibits distinct characteristics based on vehicle ownership rates and regulatory adoption. Asia Pacific remains a critical region, driven by high vehicle production volumes and increasing awareness of child safety standards. Europe continues to be a mature market where regulations like i-Size drive consistent demand for compliant mounts. North America presents a specific regulatory environment focused on FMVSS compliance and side-impact enhancements.
Latin America and the Middle East and Africa represent emerging vectors where vehicle fleet modernization and the import of safety-standard-compliant vehicles are gradually increasing the uptake of ISOFIX systems. However, the pace of adoption in these regions is influenced by economic factors and the penetration of standardized child restraint systems. Strategic expansion into these regions requires a nuanced understanding of local regulatory enforcement and consumer behavior regarding child safety.
Conclusion: The Value of Detailed Intelligence
The Automotive ISOFIX Mounts Market is at a intersection of regulatory pressure, technological evolution, and steady market growth. The projected increase to over 1.6 billion USD by 2032 offers significant opportunity, but realizing this value requires navigating complex compliance landscapes and supply chain dynamics. The upcoming changes in FMVSS 213a and potential evolutions in UNECE standards mean that static strategies will fail.
Engine Mounts Market
For executives and strategy teams, the high-level trends are clear, but the path to capturing market share lies in the details. Which specific vehicle segments are driving the highest growth rates? How do supply chain vulnerabilities in specific regions impact lead times? What are the precise design constraints imposed by the new side-impact regulations?
Worldwide Automotive ISOFIX Mounts Market
Our full Worldwide Automotive ISOFIX Mounts Market research report delves into these specifics. It provides the segmented data, the competitive profiles, and the granular forecast models necessary to build a robust strategic plan. We invite you to access the complete study to unlock the full depth of this intelligence and ensure your organization is positioned to lead in the next era of automotive safety.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ISOFIX Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copaiba Oil Market Hits $148.5M in 2025, Projects 7.2% CAGR to $241.6M by 2032
By pmarketresearch, 2026-09-16
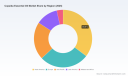
Strategic Horizons: Navigating the Global Copaiba Essential Oil Market Through 2032
The global essential oils sector stands at a critical inflection point, where botanical versatility meets escalating demand for clean, sustainable ingredients across wellness, cosmetic, and pharmaceutical verticals. Within this complex landscape, Copaiba essential oil has emerged as a compelling asset class, driven by its unique chemical profile, traditional therapeutic applications, and growing integration into modern consumer products. As industry participants prepare for the next cycle of growth, understanding the macroeconomic trajectory, competitive architecture, and regulatory undercurrents of this niche market is no longer optional—it is a strategic imperative.
Our latest Worldwide Copaiba Essential Oil Market research provides a rigorous, data-driven framework for stakeholders aiming to capitalize on the projected expansion through 2032. This overview outlines the market's historical momentum, near-term catalyst landscape, competitive positioning, and the analytical depth embedded in our full report. The objective is to equip executives, procurement leaders, and product developers with the contextual intelligence required to make informed, forward-looking decisions in an increasingly fragmented and sustainability-centric value chain.
Worldwide Copaiba Essential Oil Market
Historical Trajectory and Forecasted Growth Dynamics
Between 2020 and 2025, the global Copaiba essential oil market established a firm foundation through expanding consumer awareness, innovative extraction methodologies, and the formalization of sustainable sourcing protocols across key origin regions. The base year assessment reflects a market that has matured beyond early-stage experimentation into a structured commercial ecosystem. Steady year-over-year valuation increases during this historical window underscore the product's successful migration from niche herbal applications into mainstream cosmetic formulations, wellness supplements, and specialty fragrance compounds.
Moving into the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of 7.2%. This trajectory signals more than incremental expansion; it indicates structural demand acceleration driven by formulation innovation, cross-industry adoption, and the premiumization of botanical ingredients. The valuation progression from the 2026 baseline through to the terminal forecast year reflects a compounding effect of new market entrants, geographic diversification, and the monetization of clinically backed or sustainably certified product variants. Stakeholders who align their supply chain resilience, brand positioning, and R&D investments with this forecasted cadence are positioned to capture disproportionate share during the growth window.
The underlying demand architecture continues to be shaped by an interplay of end-use breadth and quality differentiation. As manufacturers seek ingredients that simultaneously satisfy sensory expectations, stability requirements, and clean-label mandates, Copaiba's dual utility as both a functional botanical and an aromatic carrier positions it advantageously. The market's evolution will increasingly reward players who can articulate clear value propositions across therapeutic, cosmetic, and industrial gradations while maintaining supply integrity and regulatory compliance.
Value Chain Architecture and Segmentation Intelligence
A nuanced understanding of the Copaiba essential oil market requires dissecting how revenue distributes across geographic territories, quality specifications, and application channels. Our analysis maps these dimensions not as isolated silos, but as interconnected nodes that dictate pricing power, sourcing strategy, and go-to-market execution. The regional landscape reveals a market where established consumer maturity and robust distribution infrastructure coexist alongside emerging demand centers that are actively building local processing capacity and import dependencies.
Demand is not evenly distributed across end-use categories. The application matrix demonstrates how cosmetic and personal care formulations currently anchor the largest share of commercial activity, capitalizing on Copaiba's emollient properties, natural aroma profile, and compatibility with clean beauty trends. Pharmaceutical and nutraceutical applications represent a secondary but rapidly evolving vector, where standardized extracts, softgel formulations, and bioactive research are opening premium pathways. Simultaneously, aromatherapy, wellness blending, and specialty flavor or fragrance uses continue to expand, supported by direct-to-consumer education and influencer-driven discovery cycles.
Cypress Essential Oil Market
Grade differentiation further modulates market behavior. Therapeutic-grade material commands heightened scrutiny around purity, traceability, and clinical or traditional efficacy claims, while food-grade and industrial-grade variants serve distinct regulatory and formulation requirements. The relative weighting of these categories influences procurement strategies, from bulk commodity hedging to specialized small-batch sourcing. Understanding how each grade interacts with regional supply availability and end-market price elasticity is essential for companies optimizing inventory allocation, contract negotiation, and product line extension.
From a supply-side perspective, the origin ecosystem remains anchored by producers operating within the Amazon biome, where oleoresin extraction from Copaifera species underpins the raw material pipeline. The integration of agroextractivist partnerships, cooperative models, and fair-trade frameworks has shifted sourcing from a purely extractive paradigm to one emphasizing sociobiodiversity preservation and community economic security. These practices are increasingly viewed not only as ethical imperatives but also as risk-mitigation instruments that stabilize long-term supply continuity amid environmental and regulatory pressures. Recent corporate disclosures reinforce this shift, highlighting collaborative sourcing journeys and low-impact harvesting protocols designed to maintain product quality while safeguarding collector livelihoods and ecosystem integrity.
Competitive Landscape: Strategic Positioning and Differentiation Vectors
The Copaiba essential oil market features a heterogeneous mix of multinational ingredient groups, regional Latin American producers, and specialized Western distributors, each competing through distinct lenses of scale, authenticity, certification, and application expertise. Competitive advantage in this space rarely stems from price alone; it emerges from the ability to reliably deliver consistent chemotype profiles, validate sustainability claims, and provide technical support tailored to downstream formulation needs.
Leading global wellness and essential oils enterprises have built expansive brand ecosystems that pair direct-to-consumer marketing with rigorous internal research initiatives. One prominent player has emphasized Co-Impact Sourcing networks that connect Brazilian Amazon communities with structured procurement pathways, translating socioenvironmental commitments into branded product lines spanning pure oils and encapsulated softgel formats. Concurrently, this company has advanced its scientific credibility by publishing detailed human clinical investigations examining cellular, molecular, and microbiome-level interactions, reinforcing a positioning rooted in evidence-informed wellness.
On the industrial and ingredients side, integrated chemical and specialty groups have leveraged local sourcing relationships to secure steady access to Amazonian raw materials while embedding sociobiodiversity and fair-trade principles into their operating models. Partnerships with cooperatives illustrate a supply chain philosophy that prioritizes transparent compensation structures and low-impact harvesting, aligning commercial output with biodiversity protection standards. These initiatives are increasingly cited in corporate sustainability communications, signaling to buyers that ethical provenance is becoming a procurement criterion rather than an optional accessory.
Specialty bulk suppliers and fragrance-focused producers occupy another strategic layer, often competing on consistency, origin transparency, certification portfolios, and technical service. Companies with established relationships across multiple origin points can buffer against seasonal or logistical variability, offering downstream formulators greater predictability. Meanwhile, organic-certified distributors and herbal-focused retailers continue to build loyalty through curated quality standards, educational content, and niche application expertise in aromatherapy and personal care. The resulting ecosystem is characterized by overlapping yet distinct value propositions, where scale, traceability, clinical or traditional validation, and format adaptability collectively determine share dynamics.
Recent corporate activity illustrates the breadth of strategic maneuvering shaping the market. High-profile sustainability partnerships have brought Amazon cooperative sourcing into sharper focus, while clinical research publications have sought to substantiate functional benefit narratives at a physiological level. For competitors and new entrants alike, these signals carry strategic weight: they demonstrate that credibility is increasingly constructed through visible supply chain ethics and scientifically grounded communication, not merely through product availability.
Regulatory, Sustainability, and Sourcing Dynamics
Market evolution in Copaiba essential oil is tightly coupled to regulatory expectations and sustainability mandates that are becoming more explicit across buyer organizations and origin jurisdictions. As end-users and brand owners incorporate biodiversity protection, ethical procurement, and traceability into vendor qualification criteria, suppliers who can document compliant harvesting practices, fair economic impact, and low ecological disturbance gain preferential access to premium contracts. This trend is especially pronounced in cosmetic and personal care segments, where clean-label narratives and responsible sourcing claims are subject to heightened consumer scrutiny and internal compliance review.
Forestry and biodiversity regulations governing the Amazon biome further influence how raw materials are harvested, transported, and certified. Producers reliant on conventional vs. cooperative or certified models face different cost structures, administrative burdens, and reputational exposure. As a result, sourcing strategy has evolved into a multidimensional challenge that balances yield stability, quality consistency, audit readiness, and community impact. Companies that invest early in supplier mapping, documentation infrastructure, and partnership transparency are better equipped to navigate volatility and demonstrate resilience to institutional buyers.
What the Full Research Delivers: Analytical Depth for Decision-Makers
Our complete market study extends far beyond high-level growth narratives. It is structured to support operational planning, competitive benchmarking, and investment prioritization across multiple functional teams. The report integrates historical baselines, forecast modeling, and segmentation intelligence into an actionable format that enables readers to assess market entry suitability, channel expansion opportunities, and supply chain optimization pathways.
Inside the full publication, stakeholders will find detailed analysis covering regional demand profiles, grade-specific commercial behaviors, and application-level adoption trends, along with quantitative estimates that clarify revenue distribution without exposing proprietary granular breakdowns in this summary. The competitive section profiles key companies by headquarters, sourcing philosophy, product formats, and strategic focus, supplemented by recent corporate developments that illuminate where incumbents are directing attention. Additional components examine raw material origins, extraction methodologies, certification landscapes, and regulatory considerations that shape procurement risk and formulation compatibility.
The research is designed for multiple use cases. Product developers can align ingredient selection with grade availability and application performance expectations. Procurement leaders can benchmark supplier types and assess sourcing model trade-offs. Commercial strategists can evaluate where differentiation through sustainability claims, clinical narratives, or format innovation is likely to yield stronger positioning. Investors and analysts can use the structural overview to frame portfolio exposure and identify segments where growth is most concentrated.
Strategic Imperatives for 2026 and Beyond
As the forecast period unfolds, several strategic priorities will distinguish adaptable organizations from those caught reacting to market shifts. First, supply chain resilience must be treated as a competitive asset. Diversifying origin relationships, verifying certification integrity, and maintaining contingency pathways can mitigate the impact of environmental, logistical, or regulatory disruptions. Second, communication credibility matters. Claims around sustainability, ethical compensation, and functional benefits increasingly require substantiation through documented sourcing practices, research integration, or certification frameworks. Third, application breadth should be approached with discipline. While cosmetic and personal care channels currently anchor volume, pharmaceutical, aromatherapy, and specialty flavor or fragrance segments offer differentiated margin profiles and require tailored technical alignment.
Companies that treat Copaiba essential oil as a dynamic ingredient platform—rather than a static commodity—will be better positioned to respond to evolving consumer expectations, formulation trends, and procurement standards. The intersection of projected growth, sustainability-driven sourcing, and application expansion creates a period where informed strategic action can yield durable advantage.
To access the complete dataset, segmentation estimates, company profiles, regional demand breakdowns, and forecast modeling that underpin this analysis, we invite decision-makers to explore the full Worldwide Copaiba Essential Oil Market research. The full report delivers the operational precision and contextual depth required to convert market intelligence into executable strategy across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Copaiba Essential Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Managed Office Market Hits $48.5B in 2025, Poised to $117.2B by 2032
By pmarketresearch, 2026-09-16
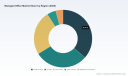
Navigating the Future of Work: Strategic Imperatives in the Global Managed Office Market
The global workplace is undergoing a structural metamorphosis. No longer viewed merely as a cost center or a static asset, the office has evolved into a strategic instrument for talent retention, operational agility, and brand expression. As organizations grapple with the enduring legacy of hybrid work models and shifting real estate economics, the managed office sector has emerged as a critical pivot point for corporate real estate strategy. Our latest Worldwide Managed Office Market research provides a comprehensive roadmap for navigating this complex landscape through 2032.
This report is not merely a collection of statistics; it is a strategic asset designed to empower C-suite executives, real estate occupiers, and investment stakeholders with the foresight necessary to make informed decisions in 2026 and beyond. By dissecting the market dynamics, competitive contours, and operational challenges, we offer clarity amidst the noise of a rapidly evolving industry.
Macro Trajectory and Market Magnitude
The managed office industry has demonstrated remarkable resilience and growth, outperforming traditional commercial real estate segments in recent years. Our analysis tracks a robust historical trajectory from 2020 through 2025, setting the stage for an aggressive forecast period extending to 2032. The market has expanded significantly from its baseline in the early 2020s, reflecting the accelerated adoption of flexible work solutions driven by technological enablement and changing workforce expectations.
Looking forward, the growth momentum is expected to sustain a strong compound annual growth rate (CAGR) over the forecast period. This expansion is underpinned by a fundamental shift in how enterprises approach space utilization. Rather than committing to long-term leases for fixed capacity, organizations are increasingly leveraging managed office solutions to align physical footprints with fluctuating headcount and project-based needs. This shift transforms office space from a liability on the balance sheet into a variable operational expense that scales with business activity.
The valuation of the market in the coming years underscores the liquidity and investor confidence in this sector. However, understanding the aggregate number is only the first step. The true strategic value lies in understanding the velocity of this growth and the specific drivers that will differentiate high-performing markets from laggards. Our research delves into these velocity drivers, offering a nuanced view of where capital and operational focus should be directed to maximize return on occupancy.
Operational Dynamics and External Pressures
The managed office ecosystem does not operate in a vacuum. It is subject to a complex web of external pressures that influence pricing, availability, and service delivery models. A primary constraint is the global office vacancy rate, which reached significant levels in late 2023. This surplus of traditional space exerts downward pressure on lease terms, forcing managed office providers to innovate their value propositions. Providers must now justify premium pricing through superior service integration, technology infrastructure, and community amenities that vacant traditional buildings cannot offer.
Labor costs represent another critical variable. The median hourly wage for facilities support services has seen upward pressure, reflecting broader inflationary trends and labor shortages in the support sector. For managed office operators, this translates to increased operational expenditures that must be managed without eroding margins or service quality. Our analysis examines how leading firms are mitigating these costs through automation and optimized staffing models while maintaining the hospitality-grade service that defines the premium managed office experience.
Regulatory environments are also tightening, particularly regarding sustainability. Emerging directives, such as those mandating minimum energy efficiency standards for non-residential buildings, will necessitate significant capital expenditure for operators managing older assets. Compliance is no longer optional; it is a prerequisite for market access in key jurisdictions. Furthermore, geopolitical factors, including export controls on IT hardware, have introduced volatility into the cost structures for technology setups within these spaces. These factors collectively shape the risk profile of entering new regions or scaling existing operations.
On the demand side, the permanence of hybrid work models cannot be overstated. A majority of global companies have institutionalized hybrid arrangements, creating a sustained demand for flexible managed offices that support distributed teams. The office is no longer the default location for every workday; it is becoming a destination for collaboration, culture building, and specialized work. Managed offices that facilitate this shift—by offering bookable collaboration zones, high-quality meeting infrastructure, and seamless technology integration—are best positioned to capture this demand.
Competitive Landscape and Strategic Positioning
The market is characterized by a diverse mix of global giants, regional specialists, and niche hospitality-driven operators. Market concentration remains relatively fragmented, meaning there is ample room for strategic differentiation and consolidation. Understanding the competitive tactics of key players is essential for both occupiers seeking partners and investors evaluating market entry opportunities.
IWG plc stands as a dominant force, operating thousands of locations under recognized brands like Regus and Spaces. Their strategy emphasizes volume and global consistency, providing fully serviced flexible workspaces that integrate IT, reception, and facilities management. Their recent financial performance highlights sustained revenue growth and continued physical expansion, reinforcing their position as a benchmark for scale in the industry.
WeWork, despite recent financial turbulence, remains a significant player in the cultural narrative of flexible work. Their restructuring efforts have focused on debt reduction and operational continuity, allowing them to maintain a presence in over 120 cities. Their emphasis on community amenities and enterprise-grade services continues to attract startups and established enterprises alike, though their financial stabilization remains a key watchpoint for partners.
Worldwide Managed Office Market
In the premium segment, companies like Servcorp and The Executive Centre focus on high-quality, furnished spaces with global IT infrastructure and concierge-level support. Servcorp's recent launch of a dedicated managed office tower in Sydney CBD exemplifies the strategy of investing in flagship assets to capture high-value tenants. Similarly, The Executive Centre leverages a strong presence across Asia-Pacific, Europe, and the Middle East to serve clients requiring luxury executive offices and day offices with robust tech services.
A newer wave of competitors includes hospitality-driven operators like Industrious and Fora. Industrious manages premium flexible workspaces tailored for enterprise teams, emphasizing hospitality-grade managed services and recent expansion into key US markets. Fora operates managed workspaces with a focus on SMBs and enterprises, offering hospitality-driven office services across numerous US locations with ambitions for global expansion. These players challenge traditional providers by elevating the user experience to match consumer hospitality standards.
Additionally, the convergence of real estate services and flexible office solutions is evident with firms like JLL Flex and CBRE FlexWork. Leveraging massive occupier relationships and provider alliances, these organizations offer managed flexible office solutions that integrate workplace strategy with on-demand management. Their approach appeals to corporate occupiers seeking scalability without the administrative burden of managing multiple providers, highlighting a trend where traditional real estate brokers are becoming active operators in the flex space.
Segmentation Nuances and Growth Vectors
A deep dive into the market reveals distinct growth vectors across space types and end-user industries. Understanding these nuances allows organizations to tailor their strategies to specific demand pockets rather than treating the market as a monolith.
In terms of space type, fully managed offices command the largest share of value. This segment appeals to enterprises seeking a turnkey solution where the provider assumes responsibility for design, fit-out, operations, and maintenance. Serviced offices represent another significant pillar, offering furnished spaces with varying levels of support. Co-working spaces, while sometimes perceived as a subset, maintain a distinct identity focused on community and ad-hoc usage. Each segment serves different risk profiles and operational requirements, and our report details the specific value drivers for each.
Smart Office Market
Demand is also unevenly distributed across end-user industries. The IT and telecommunications sector remains a primary driver, reflecting the talent-intensive nature of the industry and its early adoption of flexible work policies. Financial services and BFSI sectors follow, often utilizing managed offices for project teams, satellite offices, or cost optimization initiatives. Retail and consumer goods, healthcare, and other sectors contribute to the diversified demand base. Each industry vertical brings unique compliance, security, and service requirements that shape the offerings of managed office providers.
Geographically, the market exhibits varying maturity levels. Established markets in North America and Europe offer stability and deep provider networks, while Asia Pacific presents high-growth potential driven by urbanization and digital transformation. Emerging regions in Latin America and the Middle East and Africa are also developing, though at different scales and paces. Navigating these regional differences requires an understanding of local regulatory frameworks, labor markets, and cultural attitudes toward flexible work.
Strategic Roadmap for 2026 Decision-Makers
The insights contained in this research are designed to translate into actionable strategy. For corporate occupiers, the report provides a framework for evaluating managed office partners based on total cost of occupancy, service level agreements, technology integration, and sustainability credentials. It helps organizations decide whether to consolidate their workspace portfolio through managed solutions or to adopt a hybrid approach that blends owned assets with flexible managed spaces.
For investors and property owners, the analysis identifies which segments and regions offer the most attractive risk-adjusted returns. It highlights the importance of asset quality, location strategy, and the ability to adapt to regulatory changes such as energy efficiency mandates. The competitive intelligence section offers a detailed look at how key players are positioning themselves, allowing stakeholders to anticipate market shifts and potential consolidation events.
Furthermore, the report addresses the operational tactics required to thrive in this environment. From managing labor cost inflation to integrating technology stacks that support seamless user experiences, the findings provide a checklist for operational excellence. The impact of macroeconomic factors, including currency fluctuations and supply chain constraints on IT hardware, is also factored into the strategic recommendations.
Conclusion and Call to Action
The Worldwide Managed Office Market is at an inflection point. The convergence of hybrid work adoption, real estate cost pressures, and technological advancement is reshaping the value proposition of flexible workspaces. Organizations that proactively understand these dynamics will secure a competitive advantage in talent attraction, operational efficiency, and financial resilience.
Our comprehensive study goes beyond high-level trends to provide the granular intelligence necessary for precise decision-making. We invite you to explore the full depth of our analysis to uncover the specific regional opportunities, competitive benchmarks, and financial forecasts that will define your strategy for 2026 and the decade ahead. Access the complete report to gain the full spectrum of intelligence required to navigate the future of work with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Managed Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Meropenem Injection Market to Reach $2.87B by 2032 at 4.21% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Meropenem Injection Market: Strategic Imperatives for 2026 and Beyond
The global landscape for critical care antibiotics is undergoing a profound transformation, driven by the convergence of patent expirations, supply chain reconfigurations, and shifting epidemiological demands. As enterprises operating within the pharmaceutical and healthcare sectors plan their strategies for 2026, access to precise, forward-looking intelligence is not merely advantageous—it is essential. Our latest research offering, the Worldwide Meropenem Injection Market study, provides a comprehensive roadmap for stakeholders aiming to navigate this complex environment. This article serves as a strategic preview, outlining the macroscopic trends, competitive dynamics, and operational realities that define the market, while illustrating why this specific analysis is a critical asset for decision-makers in the coming year.
Market Trajectory and Growth Dynamics
To understand where the market is heading, one must first appreciate the trajectory it has established over the past half-decade. Our analysis covers historical performance from 2020 through 2025, establishing a robust baseline before projecting forward into the forecast period extending to 2032. The data indicates a steady expansion in market value, reflecting the enduring necessity of carbapenem antibiotics in treating severe bacterial infections.
Starting from a baseline in the early 2020s, the market has demonstrated resilience despite global supply chain disruptions and varying regulatory environments. By 2025, the market had reached a significant milestone, positioning itself for continued growth into the forecast horizon. Looking ahead, the market is expected to expand at a Compound Annual Growth Rate (CAGR) of approximately 4.21 percent. This growth is not linear; it is punctuated by specific inflection points related to product approvals, generic entries, and regional healthcare access improvements. For instance, the valuation in the immediate forecast year of 2026 reflects continued adoption, while long-term projections suggest accelerating value creation as newer manufacturing capacities come online and healthcare infrastructure in emerging economies matures.
However, growth alone does not tell the whole story. The market structure is evolving. Concentration metrics suggest that while a core group of players maintains significant influence—indicated by a top three concentration ratio exceeding 40 percent—the barrier to entry has lowered substantially following the expiration of key original patents. This shift from a branded-dominated landscape to a generic-rich ecosystem creates both opportunities for cost-efficient suppliers and risks for those reliant on fragile supply chains.
Operational Landscape: Distribution and Indication
The commercial realization of meropenem products is heavily dependent on how these injections reach the patient and the specific clinical scenarios driving their prescription. Our research dissect the market across critical operational dimensions, providing clarity on where volume and value are generated.
Worldwide Sulbactam Acid Market
Distribution channels play a pivotal role in market accessibility. Hospital pharmacies remain the dominant conduit for meropenem injections, reflecting the nature of the drug's administration which often requires supervised intravenous delivery in acute care settings. This channel captures the largest share of market activity, underscoring the importance of strong institutional relationships and reliable bulk supply mechanisms. Retail pharmacies and online pharmacies represent additional avenues, though their relative contribution varies by region and healthcare system structure. Understanding the nuances of these channels is vital for companies optimizing their sales networks and logistics partnerships.
On the demand side, the clinical indications driving consumption are diverse but concentrated around specific high-burden infections. Intra-abdominal infections represent a substantial portion of the clinical need, followed by complicated skin and structure infections. The treatment of bacterial meningitis also remains a critical use case, particularly given recent regulatory approvals expanding the utility of certain formulations for pediatric populations. By analyzing these indication segments, stakeholders can identify where therapeutic demand is most stable and where clinical guidelines might shift consumption patterns.
Competitive Dynamics and Recent Industry Shifts
The competitive arena for meropenem injections has become increasingly crowded since the original patents expired. This has enabled widespread generic manufacturing and the entry of multiple suppliers, altering the power dynamics within the industry. Our report provides a granular analysis of the key companies shaping this landscape, from established global giants to specialized generic manufacturers.
Worldwide Meropenem Injection Market
Several recent developments highlight the velocity of change in this sector. In early 2025, a major pharmaceutical company launched meropenem for injection in the United States in specific dosage strengths, manufactured through strategic partnerships with production facilities in Asia. This move underscores the trend of leveraging global supply chains to access high-value markets. Similarly, in mid-2025, another manufacturer received FDA approval for a higher-strength 2g formulation, marking a first for this specific strength in the US market and expanding options for treating severe infections including pediatric bacterial meningitis. These events illustrate how regulatory milestones can rapidly reshape market share potential.
Other key players continue to strengthen their positions through various strategies. Some focus on supplying the active pharmaceutical ingredient (API) while others concentrate on finished dosage forms. Major manufacturers based in Italy and India maintain significant roles as suppliers of both API and finished products, with multiple FDA listings supporting global distribution. Companies headquartered in Europe and North America continue to market generic versions, often relying on outsourced manufacturing networks to maintain competitiveness. The presence of suppliers from South Korea, China, and Taiwan further diversifies the supply base, though it also introduces complexities regarding quality assurance and geopolitical supply risks.
It is noteworthy that the original branded formulations in the US have been discontinued, leaving the market entirely to generic competitors. This shift places a premium on manufacturing efficiency, regulatory compliance, and supply chain reliability. Companies that can secure consistent API sourcing while maintaining strict quality standards are best positioned to capture value in this generic-dominated landscape.
Supply Chain Vulnerabilities and Regulatory Considerations
While the market offers growth opportunities, it is not without significant structural risks. Our analysis delves deep into the supply chain dynamics that underpin the availability of meropenem injections. A critical finding is the concentration of API production among a limited number of manufacturers, many of which are based in China and India. This concentration creates potential vulnerabilities, as over 80 percent of global intermediates for antibiotic APIs originate from a small number of production clusters. For procurement leaders and supply chain strategists, this represents a key area for risk mitigation and diversification.
Regulatory factors also continue to influence market operations. Recent updates to FDA labeling for certain meropenem for injection products have revised warnings and precautions, requiring manufacturers to ensure compliance and clear communication with healthcare providers. Furthermore, the discontinuation of original brand formulations in key markets like the US has consolidated the landscape around generic options, making regulatory approvals such as ANDAs critical gateways to market entry. Our report examines how these regulatory currents affect market timing and competitive positioning.
For strategic planners, understanding these dynamics is crucial. The interaction between raw material sourcing, manufacturing capacity, and regulatory approval timelines creates a complex web of dependencies. Companies must balance the cost advantages of sourcing from concentrated manufacturing hubs with the risks of supply disruption. The report provides frameworks for evaluating these trade-offs, helping organizations build more resilient procurement strategies.
Why This Research Matters for 2026 Decision-Making
As we move into 2026, the decisions made today regarding market entry, partnership selection, capacity investment, and risk management will determine competitive success in the years ahead. The Worldwide Meropenem Injection Market study is designed to support these high-stakes decisions with data-backed insights.
This research does more than report market size and growth rates. It offers a detailed examination of the forces shaping the industry. For product managers, it clarifies the competitive set and identifies gaps in formulation coverage. For supply chain directors, it maps the concentration risks and highlights the key nodes in the global API network. For investors and strategists, it provides a view on which indication segments and distribution channels offer the most stable returns.
The macroeconomic environment also adds urgency to having accurate forecasts. With market valuations projected to evolve through 2032, organizations need to know not just where the market is, but where it is going. The projected growth trajectory suggests that while the immediate forecast year shows steady progress, the longer-term outlook indicates potential acceleration as healthcare systems expand and treatment protocols evolve. Understanding the timing of these shifts allows companies to align their resource allocation with market opportunities.
Moreover, the report addresses the operational realities of the market. It explores how regional differences influence demand patterns and how distribution channel preferences vary across geographies. This level of detail is essential for companies planning market expansion or seeking to optimize their existing footprint. Generic competition is intense, and success often depends on subtle advantages in logistics, regulatory speed, or clinical support rather than price alone.
Conclusion
The global meropenem injection market stands at a pivotal juncture. The expiration of original patents has democratized access but also intensified competition. Supply chain concentration introduces fragility into an otherwise growing market. Regulatory updates continue to refine the boundaries of safe and effective use. In this environment, generic intelligence is insufficient. Leaders need a deep, structured understanding of the interplay between clinical demand, manufacturing realities, and competitive maneuvers.
Our forthcoming publication, the Worldwide Meropenem Injection Market study, delivers this depth. It integrates historical data, forward-looking projections, and a detailed analysis of the key players and dynamics that define the industry. For executives, analysts, and strategists preparing for 2026 and beyond, this report offers the clarity needed to make informed, confident decisions. We invite you to explore the full research for comprehensive data, detailed segmentation analysis, and the strategic frameworks necessary to navigate this critical segment of the pharmaceutical market.
For detailed analysis of this topic, please visit the official page: Worldwide Meropenem Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Packaging Reel Market Hits $1,450M in 2025, Forecasts 5.18% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Packaging Reel Market: Navigating Growth and Compliance in 2026
The global packaging landscape is undergoing a structural transformation, driven by intensifying sustainability mandates, volatile raw material economics, and shifting supply chain geographies. For executive leaders and strategy teams, understanding the trajectory of the Worldwide Packaging Reel Market is no longer optional. It is a critical input for capital allocation, product development roadmaps, and risk mitigation strategies heading into 2026.
This article serves as a strategic precursor to our comprehensive Worldwide Packaging Reel Market research report. The following analysis outlines the macro-economic forces, competitive pressures, and regulatory inflection points defining the sector. While we highlight the market's direction and the depth of our upcoming intelligence, specific segment valuations and granular forecasts are reserved for the full study. Leaders who secure access to the complete dataset will gain a distinct advantage in positioning their organizations for the forecast period.
Packaging Market
Market Trajectory and Macro-Economic Foundations
The packaging reel market has demonstrated resilience and steady expansion over the past half-decade. Historical analysis from 2020 through the base year of 2025 reveals a market that has successfully navigated supply chain disruptions and material cost fluctuations. The sector has matured, moving from reactive recovery to proactive growth strategies centered on efficiency and material innovation.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. Our analysis projects a Compound Annual Growth Rate (CAGR) of 5.18 percent across the forecast horizon. This growth trajectory suggests that the market will expand from its 2026 baseline of approximately 1,497 million USD to reach over 2,064 million USD by 2032. For strategic planners, this represents a significant total addressable market expansion, albeit one that will be unevenly distributed across regions and applications based on local regulatory adoption and industrial output.
The market size data underscores a critical narrative: value is accumulating, but the composition of that value is shifting. Early historical periods saw volatility, with contractions and expansions reflecting global economic conditions. However, the trend from 2023 onward shows a clear upward vector. This stabilization provides a reliable foundation for long-term investment decisions, provided companies account for the regulatory and material dynamics that will shape future revenue streams.
Regulatory and Operational Dynamics Shaping 2026
No strategic assessment of the packaging reel market is complete without addressing the regulatory environment. The years ahead will be defined by compliance costs, material substitution pressures, and cross-border trade friction. Three key regulatory themes dominate the landscape for 2026 planning.
- Sustainability Mandates and Reusability Targets. The European Union's Packaging and Packaging Waste Regulation introduces strict requirements, including a mandate for 10 percent reusable packaging share by 2030. This directly impacts reel formats used in industrial and logistics applications, pushing manufacturers and converters to evaluate returnable and durable reel systems. Companies operating in or exporting to Europe must model the operational implications of this shift, including reverse logistics costs and reel lifecycle management.
- Recycled Content and Tax Incentives. Taxation policies are rapidly aligning with circularity goals. In the United Kingdom, the Plastic Packaging Tax rate is set at £217.85 per tonne for items containing less than 30 percent recycled content. This creates a clear financial incentive to integrate recycled resin into reel production or to source reels that meet the threshold. Similarly, California SB 1013 requires all single-use plastic packaging to be recyclable by 2032, a mandate that encompasses films and reels derived from film stock. These requirements are reshaping procurement criteria and forcing material innovation.
- Trade and Tariff Pressures. Geopolitical factors continue to influence cost structures. US Section 301 tariffs impose 25 percent duties on Chinese-origin plastic packaging films and reels. For North American buyers and importers, this alters the cost-benefit analysis of offshore sourcing versus domestic or near-shore production. Strategic sourcing decisions in 2026 must factor in tariff exposure, lead time variability, and the potential for supply chain reconfiguration.
These dynamics are not isolated. They interact with raw material economics, such as the recent decline in HDPE resin prices for packaging films to $0.92 per pound in North America during Q1 2024. While lower resin costs can improve margins, they also invite scrutiny from regulators and consumers regarding the environmental profile of plastic-based solutions. The strategic imperative is to balance cost efficiency with compliance and brand positioning, a balance that requires precise data on material substitution pathways and cost modeling.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of global multinationals and specialized regional players, with concentration metrics indicating a moderately consolidated environment. The CR3 stands at 38.45 percent and the CR5 at 52.1 percent, suggesting that while leading firms hold significant share, a substantial portion of the market remains distributed among mid-tier and niche suppliers. This structure creates opportunities for both consolidation and differentiation, depending on a company's capabilities in material science, geographic reach, and customer intimacy.
Worldwide Packaging Reel Market
Leading organizations are actively reshaping their portfolios to address the trends outlined above. Several recent developments illustrate the strategic directions being taken by key participants:
- Material Innovation and Circular Design. Amcor exhibited recyclable mono-material film reels at PACK EXPO International in October 2024, signaling a shift toward formats that simplify recovery and recycling. Mondi launched the Advantage Reel Wrapper, a recyclable paper-based reel cover, in September 2023, showcasing paper-plastic hybrid and mono-material approaches for sustainable flexible packaging. Berry Global introduced NatureWorks-based bio-resin film reels in May 2023, expanding the use of bio-based feedstocks in flexible applications.
- Performance and Application-Specific Engineering. Uflex showcased a new generation of BOPP reels with enhanced printability at PlastIndia in February 2024, reflecting ongoing investment in surface performance and converter usability. Huhtamäki continues to offer high-barrier EVOH and PA co-extruded film reels for extended shelf-life food packaging, addressing the demand for preservation and waste reduction. Constantia Flexibles provides aluminum-laminated and plastic film reels for premium consumer and medical packaging, while Coveris specializes in fresh food flexible film reels with high puncture resistance.
- Diversified Regional Footprints. Companies such as Sealed Air supply Cryovac multilayer shrink and barrier film reels for protein packaging, leveraging scale and technical expertise. Sonoco delivers flexible packaging reel stock including stand-up pouch precursors, supporting a broad range of end-use formats. Winpak manufactures medical-grade and food-safe barrier film reels, while Inteplast supplies PE stretch and shrink film reels for industrial packaging. In the Asia-Pacific region, Uflex exports BOPET, BOPP, and metalized film jumbo reels to global converters, and Cosmo Films produces thermally laminatable BOPP and BOPET reels for overwrap and label applications. These regional capabilities are increasingly relevant as buyers seek to mitigate tariff risk and shorten supply chains.
The competitive game is shifting from pure price competition to value-based differentiation. Suppliers that can demonstrate compliance with recycled content thresholds, offer mono-material or recyclable formats, and provide application-specific performance will capture premium positioning. Conversely, undifferentiated commodity reel products face margin compression and heightened exposure to regulatory and tariff headwinds. Our full report provides a detailed competitive profiling framework, including capability mapping and strategic group analysis, to help leadership teams benchmark their position and identify partnership or acquisition targets.
Segmentation Themes and Growth Vectors
While the aggregate market growth is compelling, the real strategic insight lies in understanding how value is distributed across materials, regions, and end-use applications. The full study deconstructs these dimensions to reveal where growth is concentrated and which segments face structural headwinds or tailwinds.
On the material axis, plastic reels continue to represent the largest share of market value, driven by their versatility, barrier properties, and integration with high-speed converting equipment. However, paper and fiberboard reels are gaining attention as brands seek to reduce plastic intensity and improve recyclability profiles. Metal reels maintain a specialized role in high-durability and precision applications. The interplay between these material categories is being reshaped by regulation, consumer preference, and total cost of ownership calculations that include waste management and compliance costs.
Regionally, the market exhibits distinct characteristics. Asia Pacific remains a central hub for both production and consumption, with strong industrial output and growing domestic demand. North America and Europe are characterized by mature markets where growth is increasingly driven by innovation, premiumization, and regulatory compliance rather than volume expansion alone. Latin America and the Middle East and Africa present emerging opportunities, though they vary significantly in terms of infrastructure readiness, regulatory frameworks, and foreign exchange exposure. The complete report provides a nuanced view of these regional dynamics without over-simplifying the heterogeneous nature of local markets.
End-use segmentation further refines the growth picture. Electronics and semiconductors represent a high-performance segment where reel quality, cleanliness, and consistency are paramount. Automotive components demand durable and traceable packaging solutions that align with stringent quality standards. Telecommunications, medical devices, and consumer goods each impose unique requirements on reel format, handling, and material properties. The medical devices segment, for example, involves higher barriers to entry and stricter validation processes, while consumer goods are more sensitive to sustainability messaging and cost pressures. Understanding the relative attractiveness of each end-use vertical is essential for prioritizing sales investments, R&D bandwidth, and capacity planning.
The Strategic Value of Granular Intelligence in 2026
For decision-makers, the difference between a directional market view and a precise, actionable intelligence package can determine the success of a product launch, the timing of a capacity investment, or the outcome of a supplier negotiation. The Worldwide Packaging Reel Market research report is designed to bridge that gap. It goes beyond top-line figures to deliver the operational detail required for strategic execution.
The report's core components include:
- Historical Reconstruction and Forecast Modeling. A rigorous reconstruction of market performance from 2020 to 2025, integrated with a bottom-up forecast model spanning 2026 to 2032. This enables scenario planning around base, upside, and downside cases, with clear drivers identified for each.
- Segmentation Deep-Dives. Detailed breakdowns by region, material, and end-use, with analysis of volume and value trends, substitution patterns, and segment-specific regulatory impacts. This allows teams to target the most attractive sub-markets and avoid over-indexed exposure to declining segments.
- Competitive Benchmarking. Profiles of key companies, including headquarters, product focus, and recent strategic moves. The report includes a structured competitive analysis that maps capabilities, geographic coverage, and strategic positioning, supporting M&A screening, partnership evaluation, and competitive response planning.
- Regulatory and Trade Impact Assessment. A synthesis of the most material regulations, taxes, mandates, and tariffs affecting reel formats, with practical guidance on compliance pathways and cost implications. This section is updated to reflect the latest policy developments and is designed to feed directly into risk registers and procurement strategies.
- Market Concentration and Structure Analysis. Metrics on concentration, alongside qualitative assessment of barriers to entry, capacity dynamics, and the role of converters and integrators in the value chain. This helps leadership teams understand where power sits in the supply chain and how to negotiate from a position of informed strength.
This depth of analysis is particularly valuable as organizations prepare for 2026. The combination of moderate market growth, regulatory complexity, and evolving competitive dynamics means that generic market narratives are insufficient. Executives need to know which subsegments offer the best risk-adjusted returns, how material substitution will affect cost structures, and where competitors are likely to pivot. The full report delivers this level of specificity, enabling data-driven decisions rather than assumption-based planning.
Conclusion: Turning Market Insight into Strategic Advantage
The Worldwide Packaging Reel Market is entering a phase where growth and complexity are intertwined. A 5.18 percent CAGR over the forecast period signals continued expansion, but the value of that growth will accrue to organizations that can navigate material transitions, regulatory requirements, and regional asymmetries with precision. The macro trajectory is favorable; the micro execution is where competitive advantage will be won or lost.
This article has outlined the strategic context and the breadth of analysis available in our upcoming study. To move from awareness to action, leaders need the full dataset: segment-level valuations, regional growth decompositions, end-use performance comparisons, and detailed competitive profiles. These insights are essential for building resilient sourcing strategies, prioritizing innovation investments, and aligning commercial plans with the realities of 2026 and beyond.
We invite strategy, procurement, and commercial leaders to access the complete Worldwide Packaging Reel Market research for a comprehensive view of the market's architecture and trajectory. The full report translates the directional signals discussed here into the granular intelligence required to make confident, forward-looking decisions in a market that rewards clarity and preparation.
For detailed analysis of this topic, please visit the official page: Worldwide Packaging Reel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sapphire Powder Market Hits USD 545.0M in 2025, Forecasts USD 889.56M by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the 2026 Market Cycle: Navigating the Worldwide Sapphire Powder Landscape
The global sapphire powder market is entering a critical inflection point. As industries from semiconductor manufacturing to advanced optics demand higher purity, tighter specifications, and more sustainable supply chains, the strategic decisions made in 2026 will define competitive positioning for the rest of the decade. Our latest Worldwide Sapphire Powder Market research report provides a comprehensive, data-backed foundation for those decisions, combining historical trajectory analysis with forward-looking forecasts that extend through 2032.
This briefing outlines the core insights embedded in the full study, demonstrates how macroeconomic and segmentation dynamics shape operational strategy, and highlights the competitive and regulatory forces that procurement leaders, R&D directors, and corporate strategists must monitor. The objective is straightforward: equip executive teams with the contextual intelligence needed to allocate capital, secure feedstock, and align product roadmaps with where the market is actually heading.
Market Trajectory and the 2026 Decision Window
Sapphire powder has evolved from a niche industrial material into a strategic enabler across multiple high-technology sectors. Historical data from 2020 through 2025 reveals a consistent upward trajectory, with market revenue climbing steadily as downstream demand matured and manufacturing capabilities expanded. The base year of 2025 anchors this growth narrative, and our forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 7.25 percent.
By 2026, the market is positioned to cross significant revenue thresholds, and the momentum carries forward with measurable acceleration in later forecast years. This trajectory is not merely a function of volume growth; it reflects structural shifts in how sapphire-based materials are specified, sourced, and integrated into advanced manufacturing workflows. For decision-makers, the implication is clear. Planning cycles that treat sapphire powder as a stable commodity input will underestimate both the cost volatility and the performance differentiation emerging in the supply base.
The forecast model accounts for multiple macro variables, including downstream capacity expansions, purity specification tightening, and regional supply-demand rebalancing. Rather than presenting a single static number, the full report maps a range of scenario-dependent outcomes that allow strategists to test assumptions around capacity utilization, pricing tolerance, and technology adoption timelines.
Segmentation Dynamics That Shape Sourcing Strategy
Understanding where demand originates and how purity requirements are evolving is essential for building resilient procurement strategies. The market is segmented across three analytical dimensions that our research evaluates in depth: geography, purity level, and application.
Geographically, the market reflects a highly uneven distribution of consumption and production capacity. Demand is concentrated in regions with mature electronics manufacturing ecosystems, advanced ceramic producers, and established optical component supply chains. The full report unpacks the regional architectures that drive this distribution, including logistics constraints, localized feedstock availability, and the strategic behavior of regional distributors and manufacturers. These regional dynamics directly affect lead times, qualification cycles, and total cost of ownership for end users.
Purity classification is equally decisive. The market separates into standard grade material, high-purity ranges typically spanning 4N to 5N, and ultra-high purity categories exceeding 5N. As sapphire crystal growth and semiconductor-adjacent applications push performance boundaries, the premium attached to higher purity grades is intensifying. Material specified for defect-sensitive crystal growth or alpha-emission-sensitive ceramic components cannot simply be substituted with standard offerings without risking yield, contamination, or performance degradation. The report quantifies how purity segmentation interacts with pricing behavior, qualification barriers, and supplier capability matrices.
Application segmentation further refines the strategic picture. Demand streams include optical and watch glass production, LED substrate manufacturing, precision abrasives and polishing workflows, and electronic and semiconductor component fabrication. Each application places distinct requirements on particle morphology, carbon content, phase composition, and batch consistency. The full study connects these application requirements to downstream adoption patterns, enabling readers to identify which demand pockets are most likely to expand, which are vulnerable to substitution, and where supplier relationships carry the greatest strategic weight.
Worldwide Sapphire Powder Market
Internal data details for each segment, including exact regional values, purity-level splits, and application-specific revenue contributions, are reserved for the complete report. This deliberate structure allows executives to first absorb the strategic architecture before drilling into the figures that matter most for their specific operating context.
Competitive Landscape and the Rise of Differentiated Supply
The sapphire powder supply base is not monolithic. It includes integrated crystal growers, specialized high-purity alumina producers, enhanced-process manufacturers, and global distributors. Our research tracks a core set of companies whose technological positioning, product architecture, and recent commercial moves illustrate the broader competitive dynamics shaping the market.
Polar Performance Materials, based in Oakville, Ontario, Canada, has built its offering around high-purity alumina powders designed as consistent, defect-resistant feedstock for synthetic sapphire crystal growth. Its CRYSTALGuard portfolio reflects a clear strategic emphasis on feedstock reliability, an increasingly important factor for growers seeking to reduce defect rates and stabilize growth cycles. The company also supplies tailored HPA powders for technical ceramics and adjacent applications, signaling a diversified but technically coherent product strategy.
Alpha HPA Ltd, headquartered in Sydney, Australia, has emerged as a company to watch because of its combination of process differentiation and aggressive capacity expansion. Its Ultra AAP series includes high-sintering, low-alpha alumina powders produced through a proprietary solvent extraction route, alongside Ultra Sapphire low-carbon synthetic sapphire materials. Recent disclosures show Japanese semiconductor customers upgrading letters of intent for high-piry alumina volumes, with additional increases anticipated. At the same time, the company has raised its sapphire sector order book for sintered HPA tablets and announced the commencement of high-volume alumina dispersion production for CMP slurries at its Stage 1 facility. These moves suggest a supplier that is simultaneously scaling volume and deepening qualification penetration in semiconductor-adjacent channels.
AdValue Technology LLC, located in Tucson, Arizona, supplies high-purity alumina powders produced via an enhanced Bayer process. Its material portfolio is positioned for sapphire and ruby crystal growth, as well as advanced ceramic and high-temperature applications. This manufacturing pathway provides a distinct cost and scalability profile, making the company relevant for buyers evaluating the trade-offs between process origin, purity consistency, and supply availability.
Juropol Sp. z o.o., with its POLYCOR subsidiary based in Ozarow Mazowiecki, Poland, approaches the market from the crystal growth side rather than the pure powder supplier angle. It sources and refines ultra-pure alumina feedstock using proprietary technology designed specifically for high-quality sapphire crystal production in LED and semiconductor applications. This vertical integration illustrates a broader tendency in the market: a growing number of participants are tightening control over feedstock specifications to protect crystal quality and reduce variability.
Goodfellow Corporation operates as a globally connected distributor of high-purity sapphire and alumina materials. Its role is particularly relevant for research, prototyping, and smaller-scale industrial applications where flexibility, material variety, and rapid fulfillment matter more than bulk commodity pricing. Distributors like Goodfellow remain important nodes in the value chain, especially for buyers who require broad material access without committing to large dedicated supply contracts.
The full report places these companies within a wider concentration framework, showing how market share is distributed among leading participants and what that concentration implies for pricing power, supply security, and negotiation leverage.
Industry Dynamics, Cost Drivers, and Sustainability Signals
Pricing, energy intensity, and environmental performance are increasingly intertwined in sapphire powder sourcing decisions. Several developments illustrate why this is no longer a peripheral concern.
On the cost side, specialized high-purity alumina grades used in sapphire growth and advanced ceramics trade within a meaningful price band that varies by purity, phase, and form factor. The range reflects not only material specifications but also the process complexity required to produce low-carbon, low-alpha, and low-impurity variants. Buyers who understand these cost drivers can better evaluate whether a premium price is justified by yield improvement, qualification risk reduction, or downstream performance gains.
Energy intensity in upstream alumina production remains a structural cost pressure. Bauxite-derived alumina production consumed a substantial share of global energy in recent years, and that baseline energy demand contributes to volatility in feedstock economics. For sapphire powder buyers, this translates into a need to anticipate cost pass-through effects, especially where conventional process routes dominate supply.
Sustainability differentiation is becoming a competitive variable rather than a compliance checkbox. One notable example is a proprietary low-carbon alumina process that lowers emissions substantially compared with traditional methods. In a market where downstream brands and semiconductor customers are increasingly scrutinizing supplier environmental profiles, such differentiation can influence sourcing decisions, qualification priority, and long-term partnership strategy. The report incorporates these signals into its broader dynamics assessment, connecting environmental performance to commercial outcomes rather than treating it as a standalone narrative.
Regulatory and specification-driven requirements are also tightening in sensitive application areas. Certain high-purity alpha alumina powders must meet strict non-detect alpha emission thresholds for use in components where uranium and thorium contamination must be minimized. These specifications add qualification complexity, but they also raise barriers to entry and reward suppliers with proven process control. The full research examines how such technical requirements shape market access and supplier selection.
Why the Full Report Matters for 2026 Strategy
Executive teams cannot afford to rely on fragmentary market signals when making sourcing, expansion, or technology-adoption decisions. The Worldwide Sapphire Powder Market research is designed to function as an operational decision-support tool, not simply a high-level overview. It integrates historical performance, forward forecasts, segmentation logic, competitive profiling, and industry dynamics into a single analytical framework.
The report's practical content includes market sizing and growth projections anchored to a clear base year and forecast horizon, segmentation analysis that distinguishes regional, purity, and application drivers, and a competitive assessment that connects company capabilities to market behavior. It also examines market concentration patterns and the implications for supply security and negotiation strategy. For strategists, this means the report can be used to answer questions such as:
- Where is demand most likely to expand, and which specification shifts are accompanying that expansion?
- How do purity and application requirements influence supplier qualification, total cost, and substitution risk?
- Which competitors are scaling capacity, pursuing differentiation, or deepening relationships with demanding downstream customers?
- What dynamics are likely to affect pricing, energy-related cost pressure, and sustainability-driven sourcing preferences?
- How concentrated is the supply base, and what does that concentration mean for procurement resilience?
The content is structured so that both broad strategic planning and functional decision-making can be supported from the same source. Corporate development teams can use it to assess market entry or partnership opportunities. Procurement and supply chain leaders can use it to map risk concentration and qualification pathways. R&D and product leaders can use it to align material specifications with market-available purity and phase options.
From Insight to Action: Accessing the Complete Intelligence
The macroeconomic trajectory, segmentation architecture, competitive signals, and dynamic cost and sustainability factors described here are only the beginning of what the full study contains. The report goes further by presenting detailed sizing tables, segmentation splits, concentration metrics, and company-level profiles that connect strategic narrative to actionable figures. These deeper layers are essential for teams that need to quantify opportunity, benchmark suppliers, and model demand under different operational assumptions.
To access the complete dataset, segmentation detail, and competitive intelligence described in this briefing, explore the full Worldwide Sapphire Powder Market research. The study is intended for decision-makers who need validated market context before committing resources in 2026 and beyond. With demand continuing to broaden across optics, LED substrates, precision abrasives, and electronic components, the organizations that act on accurate, structured intelligence will be best positioned to manage cost, quality, and supply resilience in a rapidly maturing market.
Sapphire Glass Market
For detailed analysis of this topic, please visit the official page: Worldwide Sapphire Powder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Achondrogenesis Market to Reach $226.75M by 2032, Growing at 5.59% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Achondrogenesis Market: Strategic Intelligence for 2026 and Beyond
Executive Overview
The global landscape for rare genetic disorder diagnostics is undergoing a significant transformation, driven by advancements in prenatal screening technologies and a heightened focus on early detection protocols. As we enter 2026, enterprises operating within the healthcare diagnostics and biotechnology sectors face a complex environment defined by rapid technological adoption and shifting regulatory standards. PW Consulting's latest worldwide market research on Achondrogenesis provides a critical compass for navigating this specialized terrain, offering the granular intelligence necessary to make informed capital allocation and product development decisions.
Achondrogenesis, a severe group of genetic disorders affecting skeletal development, presents unique challenges and opportunities for diagnostic providers. The market is not merely a reflection of disease prevalence but is increasingly shaped by the sophistication of testing methods, the accessibility of prenatal care, and the strategic positioning of key industry players. Understanding the trajectory of this market is essential for stakeholders aiming to secure a competitive edge in a niche yet high-impact segment of the broader genetic testing industry. This report serves as a comprehensive resource, distilling years of historical data and forward-looking analysis into actionable strategic insights.
Market Trajectory and Growth Dynamics
The financial contours of the Achondrogenesis market reveal a steady expansion trajectory that underscores the growing demand for specialized diagnostic solutions. Analysis of historical performance from 2020 to 2025 indicates a market that has demonstrated resilience and consistent growth despite broader economic fluctuations. In 2020, the global market revenue stood at approximately 118.25 Million USD. Over the subsequent five years, the sector navigated various operational challenges and technological shifts, reaching a valuation of 155.0 Million USD by 2025. This historical baseline establishes a robust foundation for projecting future performance.
Activin A Market
Looking ahead, the forecast period spanning 2026 to 2032 suggests continued momentum, albeit with varying rates of acceleration across different phases. The market is projected to reach 161.36 Million USD in 2026, reflecting a modest initial step as organizations integrate new findings and adjust strategies. Growth is expected to compound over the following years, with valuations climbing to 169.56 Million USD in 2027 and 172.99 Million USD in 2028. A more pronounced expansion is anticipated towards the end of the forecast window, with the market potentially reaching 198.35 Million USD by 2029 and 213.56 Million USD by 2030. While some fluctuations may occur, such as the slight adjustment projected for 2031 to 204.98 Million USD, the long-term outlook remains positive, culminating in an estimated 226.75 Million USD by 2032.
Central to this outlook is the Compound Annual Growth Rate (CAGR), which serves as a key indicator of sustainable expansion. The market is characterized by a CAGR of 5.59 percent throughout the forecast period. This rate signals a mature but actively growing sector where innovation and efficiency gains are primary drivers. For corporate strategists, this CAGR implies that passive observation is insufficient; active engagement and investment in capability enhancement are required to capture share in a market that is incrementally but steadily enlarging. The revenue unit is consistently tracked in Million USD, providing a standardized metric for financial planning and benchmarking against peer industries.
Segmentation Insights and Operational Focus
A deeper understanding of the market structure requires an examination of how value is distributed across different operational dimensions. The segmentation analysis within the report highlights distinct areas of activity that define the competitive landscape. By examining the split across various categories, organizations can identify where the greatest volume of activity resides and where strategic focus should be directed.
Diagnostic and Imaging Modalities
The market is heavily influenced by the types of diagnostic procedures utilized for detection and confirmation. Genetic Testing represents a dominant segment, reflecting the critical role of molecular analysis in identifying the underlying mutations associated with Achondrogenesis. This area commands significant attention due to the precision required and the ethical implications of genetic counseling. Prenatal Ultrasound Imaging constitutes another substantial portion of the market activity, serving as a primary screening tool that often triggers further genetic investigation. The reliance on imaging underscores the importance of radiological expertise and equipment availability in clinical settings. Additionally, Histopathology and Autopsy remain relevant components of the market structure, particularly in post-natal confirmation and research contexts, though their relative share differs from the proactive screening methods.
End-User Ecosystems
The distribution of market activity across end-user groups reveals where the demand is most concentrated. Hospitals represent the primary hub for Achondrogenesis-related diagnostics and care, absorbing the largest share of operational volume. This concentration highlights the importance of hospital procurement cycles, integration with electronic health records, and the need for solutions that fit within busy clinical workflows. Diagnostic Centers form another critical pillar, offering specialized services that may not be available within general hospital settings. These centers often cater to referral networks and provide high-throughput testing capabilities. Academic and Research Institutes also play a vital role, contributing to the market through studies, protocol development, and the training of specialized personnel. Their involvement ensures that the market remains connected to scientific advancements and emerging best practices.
Geographic Distribution
Regional dynamics further shape the market landscape, with activity distributed across major global territories. North America exhibits significant market presence, driven by established healthcare infrastructure and high adoption rates of advanced diagnostic technologies. Europe follows as a major region, characterized by robust regulatory frameworks and a strong emphasis on prenatal care standards. The Asia Pacific region represents a growing area of interest, where expanding healthcare access and increasing awareness are contributing to market development. Latin America and the Middle East and Africa also contribute to the global total, though their individual shares reflect different stages of market maturity and infrastructure development. Understanding these regional nuances is crucial for organizations planning international expansion or seeking to diversify their revenue streams.
Competitive Landscape and Industry Concentration
The structure of the market suggests a moderately concentrated environment where strategic positioning is key to maintaining stability and growth. Industry concentration metrics indicate that the top three players account for approximately 38.5 percent of the market, while the top five entities hold around 52.15 percent. This distribution implies that while there is room for niche players and specialized providers, a significant portion of the market activity is influenced by a core group of established organizations.
For enterprises evaluating potential partnerships, acquisitions, or competitive responses, understanding this concentration is vital. The presence of dominant players often sets standards for pricing, quality, and service levels that smaller entities must navigate. However, the remaining market share available to other participants suggests opportunities for differentiation through specialized services, regional focus, or innovative testing protocols. The competitive landscape is not static; it evolves as companies invest in research, expand their service portfolios, and adapt to changing clinical guidelines. Stakeholders must remain vigilant about shifts in market share and emerging entrants that could disrupt existing dynamics.
Strategic Value for 2026 Decision-Making
In the context of 2026, this market research report offers more than just historical data; it provides a framework for proactive strategy formulation. The transition from 2025 to 2026 represents a pivotal moment where organizations must align their resources with projected growth areas and potential challenges. The insights contained within the report are designed to support decision-making across multiple functional areas.
Resource Allocation and Investment
Financial leaders can utilize the growth projections and segmentation data to prioritize investments in high-potential areas. Knowing which diagnostic modalities and end-user segments drive the most activity allows for targeted capital deployment. For instance, strengthening capabilities in genetic testing or enhancing ultrasound imaging partnerships may yield higher returns depending on an organization's specific strategic positioning. The forecast data helps in budgeting and forecasting, reducing uncertainty in long-term financial planning.
Product and Service Development
R&D and product teams can leverage the report to identify gaps in the current market offering. The emphasis on specific diagnostic types and end-user needs highlights where innovation is most needed. Whether it involves developing more efficient testing protocols, improving imaging resolution, or creating user-friendly interfaces for clinical staff, the market intelligence guides the innovation pipeline. Aligning product development with the documented market trajectory ensures that new offerings are relevant and timely.
Risk Management and Compliance
Worldwide Achondrogenesis Market
Operating in the rare disease diagnostic space requires careful attention to regulatory and ethical considerations. The report provides context on the industry environment that can help organizations anticipate compliance requirements and manage reputational risks. Understanding the competitive concentration and regional variations also aids in assessing operational risks associated with market entry or expansion. Proactive risk management is essential for maintaining trust with healthcare providers and patients alike.
Core Report Contents and Deliverables
To ensure that stakeholders have access to the depth of information required for rigorous analysis, the report encompasses a wide range of operational and strategic content. The deliverables are structured to support both high-level strategic reviews and detailed tactical planning.
- Comprehensive market sizing and forecast models that break down revenue trends over the historical and forecast periods.
- Detailed segmentation analysis covering diagnostic types, end-user categories, and regional distributions to identify growth pockets.
- Competitive landscape assessment that maps out the market structure, concentration levels, and the positioning of key participants.
- Analysis of industry drivers, restraints, and opportunities that influence market dynamics and future performance.
- Strategic recommendations tailored to different stakeholder groups, including investors, providers, and technology developers.
- Insight into regulatory and technological trends that are shaping the evolution of Achondrogenesis diagnostics.
Each section of the report is designed to build a cohesive narrative that connects market data with real-world implications. The integration of historical context with forward-looking projections allows readers to understand not just where the market has been, but where it is heading and what actions are necessary to succeed.
Conclusion: Securing a Competitive Edge
The Worldwide Achondrogenesis Market represents a specialized yet strategically significant segment of the global healthcare diagnostics industry. As we move through 2026, the ability to interpret market signals and act on them with precision will distinguish leading organizations from those that merely follow. The growth trajectory, characterized by a steady CAGR and expanding revenue base, indicates that there is substantial value to be captured by those who invest in understanding the market's nuances.
However, navigating this landscape requires more than surface-level knowledge. It demands access to detailed segmentation data, competitive intelligence, and forward-looking analysis that only a comprehensive research study can provide. The insights summarized here offer a glimpse into the strategic value embedded within the full report, but the complete picture requires a deeper dive into the specific data points, regional breakdowns, and competitive assessments that drive actionable decision-making.
Organizations seeking to maximize their potential in this market are encouraged to access the full Worldwide Achondrogenesis Market research study. By doing so, they will equip themselves with the authoritative intelligence needed to formulate robust strategies, mitigate risks, and capitalize on the opportunities that lie ahead in 2026 and beyond. The future of this market belongs to those who are prepared, informed, and ready to act on the best available evidence.
For detailed analysis of this topic, please visit the official page: Worldwide Achondrogenesis Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sports Lingerie Hits $13.5B in 2025, Set to Reach $24.7B by 2032 at 8.98% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Sports Lingerie Market: Navigating Growth from 2026 to 2032
The athletic intimate apparel sector has evolved from a peripheral activewear category into a central pillar of modern lingerie demand. As consumers fuse performance expectations with lingerie aesthetics, manufacturers and retailers must interpret market signals with precision. Our latest Worldwide Sports Lingerie Market study delivers a structured, forward-looking intelligence framework designed to support enterprise decision-making across the 2026 to 2032 horizon. This report does more than track historical sizing. It translates demand shifts, channel migration, and competitive signaling into operational context that boards, procurement leaders, and brand strategists can act upon immediately.
For organizations evaluating capacity expansion, product portfolio redesign, or channel reallocation, understanding the base trajectory is only the starting point. The strategic value lies in interpreting how macroeconomic momentum, product-type performance, regional demand patterns, and competitive behavior intersect within a single analytical system. In that sense, this study functions as a decision-support infrastructure rather than a static sizing exercise. By anchoring the analysis in a robust historical baseline and extending it across a multi-year forecast window, the report equips stakeholders with the reference points needed to model scenarios, set pricing architectures, and prioritize investments in the most responsive segments of the sports lingerie ecosystem.
Macro Momentum and What It Means for 2026 Decision-Making
The historical record establishes a clear expansion narrative. Between the early 2020s and the 2025 base year, global revenue in sports lingerie progressed through a sustained upward curve, reflecting the category's deepening integration into everyday activewear routines, premiumization trends, and cross-channel availability. Building on that trajectory, the forecast period projects continued growth, with an implied compound annual growth path that distinguishes sports lingerie from several broader apparel segments experiencing slower structural expansion.
For strategic planners, the key implication is not simply that the market is growing, but that the growth environment demands differentiated responses. A rising revenue curve attracts new entrants, intensifies promotional activity, and sharpens buyer expectations around fit, fabric performance, and brand authenticity. Organizations that rely on legacy sizing assumptions risk misaligned inventory planning and underinvested innovation pipelines. Instead, enterprise decisions in 2026 should be calibrated to a market where volume gains are likely to be accompanied by compositional change: shifts in product emphasis, distribution leverage, and consumer willingness to pay for technical comfort.
This report frames that environment through a multi-year forecast that extends well beyond the immediate fiscal cycle. By layering forward estimates across the forecast horizon, the analysis helps executives test assumptions about demand durability, category penetration, and the pacing of adoption across different shopping behaviors. The result is a more reliable foundation for revenue planning, capacity timing, and strategic prioritization than ad hoc trend extrapolation can provide.
Report Architecture: Operational Intelligence Rather Than Passive Sizing
The Worldwide Sports Lingerie Market study is built to be used, not merely referenced. It provides a comprehensive analytical toolkit organized around the dimensions that most directly shape commercial execution. The report integrates historical performance, forecast modeling, segmentation structure, competitive profiling, and supply-side context into a coherent intelligence package. Each section is designed to support specific decision types, from innovation roadmapping to channel strategy and risk assessment.
Nursing Bras Market
At the structural level, the analysis examines the market through multiple lenses that matter to operating teams:
- Demand distribution across core product categories in the sports lingerie space, including sports bras, performance briefs and shorts, and other athletic intimate offerings, providing context for portfolio allocation and innovation focus.
- Distribution-channel dynamics spanning online retail, specialty stores, and department stores, with emphasis on how channel mix influences reach, margin structure, and assortments strategy.
- Regional market architecture covering North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, giving executives a basis for geographic prioritization and market-entry evaluation.
- Market concentration parameters that help clarify the balance between established players and the space available for challengers or niche differentiation.
Beyond the segmentation structure, the report includes competitive profiles that connect corporate positioning with product and technology strategies. Instead of presenting company information as isolated fact sheets, the study places each organization in the context of its strategic posture, product emphasis, and likely response patterns within the sports lingerie category. This allows leadership teams to benchmark peer behavior, anticipate competitive moves, and identify white space where differentiation can be built on fabric innovation, fit engineering, or brand positioning.
Supply-chain and materials context is also embedded in the analysis. Because athletic intimate apparel depends heavily on engineered stretch, moisture management, and durability, raw material behavior has direct implications for cost planning and product design. The report integrates relevant material-market signals so that commercial and sourcing teams can interpret pricing trends, fiber composition dynamics, and sourcing considerations as part of the same strategic picture rather than as disconnected inputs. In addition, regulatory and safety expectations are addressed where relevant, helping organizations anticipate consumer scrutiny and compliance realities that can affect brand trust and product acceptance.
The study also accounts for recent industry activity that shapes near-term interpretation. Product launches, innovation announcements, and major trade-show participation all provide evidence about where attention and investment are flowing within the category. By incorporating these developments into the broader analytical frame, the report helps readers distinguish transient noise from structural momentum and identify the areas where innovation is becoming category-defining rather than merely incremental.
Competitive Landscape: Strategic Positioning in a Fragmented Field
The sports lingerie category is shaped by a broad group of participants spanning performance-driven apparel manufacturers, intimate apparel specialists, and crossover brands that bridge athletic and lifestyle positioning. This diversity creates both opportunity and complexity. A company's strategic challenge is rarely only to compete on product quality; it is also to choose where to compete, how to articulate value, and which consumer expectations to prioritize. The report's competitive analysis is designed to support exactly those choices.
Large global sportswear and athletic brands continue to play a central role. Players such as Nike, Adidas, and Under Armour anchor significant portions of the conversation around performance engineering, moisture management, and fabric innovation. Their product approaches often emphasize technical support, seamless construction, and material systems designed for demanding activity. At the same time, premium athletic lifestyle brands such as Lululemon Athetica have strengthened the category's high-support, comfort-focused segment through product development that targets both performance and wearability. Recent product introductions in this space illustrate how brands are widening the definition of sports lingerie to include ultrarunning-grade support, lightweight feel, and advanced construction methods.
Parallel to these performance-led players, a second competitive layer includes brands rooted in intimate apparel, value-driven basics, and inclusive lifestyle positioning. Companies such as Hanesbrands, Victoria's Secret & Co., Triumph International, Wacoal Holdings, and American Eagle Outfitters represent distinct strategic routes into the category, ranging from heritage intimate expertise to body-positive crossover styles. Their inclusion matters because they influence demand expectations beyond pure athletic performance, expanding the category's relevance into everyday comfort, fashion adjacency, and value-conscious purchasing. On the more accessible side, retailers and sporting-goods players such as Decathlon and Puma contribute to broader availability and lifestyle-oriented product blending, while running-focused specialists such as ASICS, New Balance, Brooks Sports, and On Holding extend the performance narrative into sport-specific support and stability.
From a strategic standpoint, the competitive landscape is less about counting participants than about understanding how their positioning choices fragment demand. Some organizations prioritize technical performance and continuity with broader sportswear ecosystems. Others build around premium comfort, inclusive branding, or price accessibility. The report maps these strategic orientations so that decision-makers can identify which competitive vectors are most crowded, which are underserved, and where brand storytelling can be aligned with tangible product differentiation. Market concentration indicators further support this reading by clarifying the share structure and helping organizations gauge the relative room for new positioning or aggressive share capture.
Raw Material and Regulatory Context: Hidden Variables in Margin and Brand Trust
Sports lingerie is materially dependent on engineered fibers and fabrics, which means that upstream market conditions influence both product economics and design feasibility. Stretch performance, durability, moisture management, and comfort all rely on specific fiber blends and construction choices, so shifts in material costs or availability can alter margin potential and product architecture. The study incorporates material-market context to help organizations interpret pricing behavior in key inputs and factor those dynamics into sourcing plans, cost models, and product roadmaps.
Worldwide Sports Lingerie Market
At the same time, consumer expectations around safety and transparency have become increasingly material to brand trust. Regulatory scrutiny and consumer watchdog attention around chemical safety in apparel items have introduced an additional layer of risk for intimate and activewear products. In a category where items are worn in close contact with the body and frequently associated with health-conscious lifestyles, safety perception is not a peripheral concern; it is part of product acceptance and brand reputation. The report integrates these considerations so that risk, compliance, and communication strategies can be developed proactively rather than reactively.
Taken together, material and regulatory signals form a strategic backdrop that reinforces the need for holistic planning. Cost structure, product performance, and consumer confidence are interconnected. A brand that advances innovation without maintaining visibility into input markets or safety expectations may find that technical gains are offset by sourcing volatility or reputational friction. The report's integrated approach helps organizations keep these variables in view while building growth strategies.
Why This Study Matters for 2026 Strategy
Effective strategic planning in sports lingerie requires more than awareness that the category is expanding. It requires a structured interpretation of how that expansion is distributed, where competitive pressure is building, and what operational variables will shape profitability and brand positioning over the coming years. The Worldwide Sports Lingerie Market study is designed to serve that need by converting broad market momentum into usable intelligence.
For product and innovation teams, the report offers context for prioritizing development efforts across product types, support levels, and fabric strategies. For commercial and channel leaders, it provides a basis for evaluating where demand is formed, how shopping behavior is shifting, and which retail environments are most relevant to assortment planning. For executive leadership and corporate strategy, it delivers a consolidated view of market scale, growth trajectory, competitive diversity, and concentration dynamics that can inform investment decisions, market-entry evaluations, and long-range planning.
Most importantly, the study is structured to support decisions under uncertainty. By combining historical evidence, forward estimates, segmentation insight, competitive profiling, and material and regulatory context, it gives organizations a wider field of view than any single metric can provide. That breadth is essential in a category where consumer behavior, brand innovation, and supply-side conditions are evolving together.
Connect to the Full Intelligence Package
This article is an introduction to the strategic framework behind our Worldwide Sports Lingerie Market research. It highlights the analytical dimensions, decision contexts, and competitive themes that make the study relevant for 2026 planning. The full report contains the detailed segmentation breakdowns, regional and channel-level interpretation, competitive profiles, and forward estimates needed to translate this framework into executable strategy.
Organizations ready to move beyond high-level momentum and into specifics will find the complete analysis valuable for scenario planning, portfolio alignment, and competitive positioning. To access the full dataset and examine the segmentation detail, regional dynamics, and company-level intelligence that support these conclusions, visit the source page for the complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Sports Lingerie Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Carbon Composite Tubes and Pipes Market Hits $496.5M in 2025, 8.5% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Structural Shift: Strategic Intelligence for the Worldwide Carbon-Carbon Composite Tubes and Pipes Market in 2026
The global industrial landscape in 2026 is defined by a convergence of extreme-performance material requirements and geopolitical supply chain recalibration. At the intersection of these forces lies the worldwide market for carbon-carbon composite tubes and pipes. This sector is no longer a niche supplier to specialized furnace builders; it has become a critical enabler for semiconductor capacity expansion, next-generation aerospace platforms, and high-efficiency industrial thermal systems. For executives, capital allocators, and R&D directors, understanding the trajectory of this market is not merely an academic exercise. It is a prerequisite for securing supply, mitigating tariff exposure, and positioning product portfolios for the decade ahead.
Worldwide Carbon Carbon Composite Tubes and Pipes Market
Carbon-Carbon Composite Material Market
Our latest market research, Worldwide Carbon Carbon Composite Tubes and Pipes Market, is designed to convert complex market signals into actionable strategy. Below, we outline the structural dynamics, competitive fault lines, and regulatory inflection points that will define decision-making throughout 2026 and the broader forecast horizon.
The Macro Trajectory: Sizing the Window of Opportunity
Over the historical window from 2020 through 2025, the worldwide revenue base for carbon-carbon composite tubes and pipes expanded from a baseline of approximately 330.5 million USD to 496.5 million USD in the most recent base year. This growth path reflects a compounding demand environment where performance tolerances are tightening and replacement cycles for high-wear thermal components are accelerating. Looking forward, the market is projected to continue its expansion through 2032, with revenue scaling toward a trajectory that underscores both volume growth and value migration toward higher-specification grades.
The forward arc is characterized by a sustained compound annual growth rate of 8.5 percent across the forecast period from 2026 to 2032. To put this in operational context, a mid-teens growth trajectory sustained over multiple years implies that the market will more than double its scale relative to the 2025 base before the close of the forecast horizon. For strategists, the implication is clear: backlog visibility, capacity reservation, and technology road-mapping must be locked in now rather than reactive to spot-market tightness later.
Embedded within this headline trajectory is meaningful volatility by segment and region. The aggregate figure masks a competitive battleground where process economics, material availability, and application-specific qualification cycles diverge sharply. This is precisely why disaggregated visibility matters. Managers who rely on top-line aggregates risk over-indexing on growth sectors that are margin-dilutive or under-indexing on stable, high-margin pockets where supplier lock-in and engineering partnerships dictate market access. Our report isolates these layers without exposing the granular figures prematurely, reserving the full dataset for clients who need to build supply plans, pricing models, and go-to-market roadmaps.
Structural Realities Shaping 2026 Strategy
Three structural forces converge to redefine how buyers and suppliers will operate in 2026 and beyond. Each carries consequences for sourcing strategy, product architecture, and regional footprint.
- Raw material architecture is stratified by precursor chemistry. PAN-based precursors continue to dominate carbon fiber production used in carbon-carbon composites, reflecting broad-based demand across non-aerospace sectors and broader composite ecosystems. At the same time, pitch-based carbon fiber precursors, valued for high-modulus and thermal properties in specialty carbon-carbon applications, are projected to grow significantly in targeted high-performance segments. This bifurcation means that tube and pipe manufacturers cannot treat raw material strategy as a commodity call. Grade selection, precursor sourcing, and densification method choice interact directly with qualification timelines and end-market acceptance.
- Regulatory friction is entering the cost equation in new ways. In the United States, effective March 2025, tariffs on carbon fiber materials from targeted countries increased to 25 percent for raw carbon fiber tow and 17.5 percent for prepreg materials under a Section 301 expansion. For a market where reinforcement materials are foundational inputs, this is not an administrative detail; it is a pricing and sourcing variable that reshapes landed cost comparisons across origins. Simultaneously, the EU Carbon Border Adjustment Mechanism is scheduled to impose fees on selected imports for greenhouse gas emissions starting in 2026. As production footprints and logistics routes are reconsidered, the carbon intensity of upstream material flows becomes a competitive variable, not just a compliance one.
- Demand-side end-use intensity is accelerating qualification and substitution. In semiconductor and solar silicon production, thermal uniformity and chemical inertness requirements are intensifying as wafer processes scale and throughput expectations rise. In aerospace and defense systems, weight-to-performance ratios and extreme-temperature resilience continue to drive engineering adoption of carbon-carbon solutions where metallic alternatives fall short. Industrial furnace operators face pressure on energy efficiency and component life, while medical and laboratory equipment manufacturers seek high-precision, low-contamination tubing for specialized thermal and vacuum environments. Each vertical carries a distinct barrier-to-entry profile, and understanding where qualification risk can be compressed versus where it remains a durable moat is central to market participation.
A recently observed market entry reinforces the innovation and commercialization tempo. In October 2025, Super Carbon Composites Technologies (SCCT) launched as a startup focused on commercialization of ultra high-density carbon/carbon composites using FAST/SPS densification for aviation, space, industrial, semiconductor, and automotive applications. New entrants pursuing advanced densification routes are not merely adding optionality; they are signaling that production economics, cycle times, and achievable density windows are still being actively contested. For incumbents and buyers alike, this underscores the need to monitor process differentiation, not just brand names.
The Competitive Architecture
The competitive field is shaped by a blend of integrated manufacturers, material suppliers, and specialized converters. Market concentration data indicate that the top three competitors collectively hold about 42.5 percent of revenue, while the top five reach approximately 58.3 percent. This profile suggests a market that is meaningfully consolidated at the top yet still broad enough in the tail for specialized players to command attractive niches through engineering depth, regional proximity, or proprietary process know-how.
Strategic mapping of the core companies reveals several archetypes that matter for 2026 planning:
- High-temperature component specialists with direct tube and pipe output. CFCCARBON CO. LTD, based in Beijing, manufactures carbon-carbon composite rods, tubes and pipes using carbon fiber reinforced carbon matrix for high-temperature applications. SHJ Carbon, headquartered in China, produces carbon-carbon composites including tubes and components for thermal applications with more than 25 years of experience in high-temperature carbon materials. Bost Carbon Materials Co. Ltd., in Hunan, operates as a high-tech enterprise producing carbon-carbon composite materials alongside rigid and soft felts for high-temperature insulation and structural applications. These players anchor the production-side base where application-specific thermal performance is the primary value driver.
- Integrated and premium-class tube manufacturers in Europe. SGL Carbon, based in Wiesbaden, Germany, is an integrated manufacturer offering carbon-based products and solutions applicable to high-performance carbon-carbon composite tubes and pipes. Carbon Composite AG, in Germany, manufactures premium-class carbon precision tubes made in Germany, focusing on high-rigidity lightweight carbon composite tubing. Epsilon Composite, located in Gaillan-en-Médoc, France, is a specialist in high-performance lightweight carbon fiber tubes and profiles via pultrusion and pullwinding, with capabilities extending to advanced carbon composites. In a context of tariff escalation and border adjustment pressure, such European-based capacity can carry strategic advantages for customers with regional compliance and logistics priorities.
- Carbon fiber and reinforcement material leaders shaping the input base. Toray Industries in Tokyo is a global leader in carbon fiber materials used as key reinforcement for carbon-carbon composite tubes and pipes in advanced applications. Teijin Limited, also in Tokyo, supplies advanced carbon fiber raw materials and prepregs supporting production of carbon-carbon composite tubes and pipes. Mitsubishi Chemical, likewise headquartered in Tokyo, provides carbon fiber divisions and materials for composite tube and pipe manufacturing including carbon-carbon variants. Hexcel Corporation, in Stamford, Connecticut, manufactures advanced composite materials including carbon reinforcements for high-performance carbon-carbon composite tubes. For downstream tube producers, the relationship with these material houses influences grade availability, qualification support, and cost stability.
The competitive reality in 2026 is not simply about who has the largest revenue base. It is about who can align reinforcement supply, densification choice, and application qualification into a defensible commercial offering. This is where our report’s competitive profiling and capability mapping become operational tools rather than static lists.
What the Report Delivers for Decision-Making
The full study is constructed to support executive, procurement, engineering, and investor use cases simultaneously. It is organized to convert macro signals into segment-level clarity, then into competitive posture and strategic options. Among the core deliverables are:
- Market sizing and forecasting that contextualizes historical evolution from 2020 through 2025 and maps the projected trajectory through 2032, with attention to the growth rate and revenue scale that frame capacity and investment discussions.
- Segment-level decomposition by region, by process type, and by application, allowing managers to isolate the pockets where volume, margin, and qualification dynamics differ and to align sourcing and product roadmap decisions accordingly.
- Process-type comparison across chemical vapor infiltration and liquid phase impregnation, including the operational and commercial implications of each route for throughput, property profiles, and application fit.
- Application-level analysis spanning semiconductor and solar silicon production, aerospace and defense systems, high-temperature industrial furnaces, and medical and laboratory equipment, with a focus on adoption drivers and barriers in each vertical.
- Regional assessment covering North America, Europe, Asia Pacific, and the rest of the world, framed by the interaction of demand geography, production location, and the tariff and border-adjustment environment.
- Competitive profiling of the core companies, with capability summaries, geographic alignment, and strategic positioning relevant to partnerships, sourcing, and market entry evaluation.
- Contextual dynamics on raw material precursors, regulatory developments, and recent industry developments such as new venture launches, woven into the market narrative to support scenario interpretation.
Crucially, the report is built to prevent over-reliance on headline numbers. Because segment splits, regional shares, and application-level revenue concentrations carry the operational nuance that top-line totals cannot, the study unpacks these layers with the level of granularity needed to inform procurement timing, negotiation leverage, and product positioning. The full detail set is available through the source page, where the complete segmentation tables, company profiles, and scenario framing can be accessed in full.
Why 2026 Is the Decision Year
The current moment is not simply another year in a growth curve. Several converging conditions make 2026 a pivotal planning window:
- Tariff and border-adjustment structures are moving from announcement to effect, altering landed-cost comparisons and prompting re-evaluation of supply origins, inventory buffers, and dual-sourcing strategies.
- Precursor mix dynamics are shifting in relevance as end-use applications demand more differentiated modulus and thermal behavior, making grade selection and supplier qualification more consequential than ever.
- Innovation entrants are advancing densification and processing options that could reshape cost and property trade-offs, meaning incumbents and buyers need to monitor technical disruption, not just price.
- Application-side demand intensity is rising across high-value verticals, increasing the importance of qualification speed, delivery reliability, and engineering partnership quality as competitive differentiators.
In this environment, executives who wait for fully matured market clarity will find themselves reacting to price spikes, allocation constraints, and qualification windows that have already closed. Those who build strategy on the back of integrated market intelligence, competitive mapping, and regulatory scenario alignment will be positioned to secure capacity, choose the right reinforcement and process architecture, and align product roadmaps with the demand cycles that matter most.
Accessing the Full Intelligence
This article is intended as a strategic preview: a demonstration of the analytical depth, structural framing, and competitive context that underpin our Worldwide Carbon Carbon Composite Tubes and Pipes Market research. It is not the full decision-support package. The complete study contains the detailed segmentation data by region, process type, and application, together with the company-level profiles, market concentration analysis, and regulatory and raw-material context needed to build sourcing plans, pricing models, and investment theses for 2026 and the forecast period through 2032.
For teams responsible for supply strategy, product development, regional expansion, or competitive positioning, the full report provides the granularity and scenario framing necessary to move from awareness to execution. The source page is where the complete dataset, segmentation splits, and detailed profiles can be reviewed and integrated into internal planning workflows. In a market where timing, qualification, and input-cost exposure are decisive, the difference between reactive and proactive strategy often comes down to data resolution. That resolution is available in the full study, and 2026 is the year to put it to work.
For detailed analysis of this topic, please visit the official page: Worldwide Carbon Carbon Composite Tubes and Pipes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com